




Amazon Stock Forecast: $8 Billion Chip Financing Report Puts AI Spending in Focus
As the market focuses on AI spending, October 2 brings a new consideration regarding Amazon (NASDAQ: AMZN). Not is it not whether they will continue to spend, but how will they fund that growth? AMZN closed at $248.23 on October 1, down 0.37%, before Reuters published a story reporting that Amazon was considering moving about $8 billion of Nvidia’s Grace Blackwell chips into a special-purpose vehicle and leasing them back. Oct 1’s closing price was not a market reaction to the funding story.
What draws my interest is the strong growth of AWS combined with rapid investment in data center and AI infrastructure. Amazon’s core business is healthy, but rapid investment has caused trailing free cash flow to rapidly decline. The stock is valued based on the next phase of the AI narrative, and whether there is a return in the cash generated from the capacity growth, or if it merely results in larger cash outflows.
Reported Nvidia Chip Financing Is Still a Proposal
According to an October 2 article in the Financial Times, and as reported by Reuters, Amazon is considering moving about $8 billion of Nvidia’s Grace Blackwell chips that it has bought or leased and is installing in U.S. data centers into a special-purpose vehicle (SPV). In the reported structure, Amazon would lease the chips back, and the SPV would seek financing through debt while Amazon could offer an equity stake of up to 10% in the vehicle. Amazon and Nvidia had not immediately commented, and the reporting indicated that the structure was still considered proposed, not announced or completed.
Although the reported structure does provide flexibility in how certain infrastructure can be financed, that does not mean there is no remaining economic obligation. The terms of the lease agreements, guarantees, and the residual value assumptions, in addition to any other support Amazon may provide to the SPV, will impact the economic return to Amazon and Amazon shareholders.
Q2 Shows Strong Operating Momentum
Amazon reported a 20% year-over-year increase in net sales to $200.6 billion for Q2 2026. Operating income increased 43% to $27.5 billion. North America sales increased 16% to $116.2 billion, International sales increased 15% to $42.2 billion, and AWS revenue increased 37% to $42.2 billion. The strength in the International and North America segments is a positive. The strength in the AWS segment provides a nice base for the further investment case.
For the quarter, operating income for AWS was $16.6 billion, North America was $9.1 billion, and International was $1.7 billion. That supports a ~39% operating margin for AWS for the quarter. In my view, it highlights the importance of the cloud business and justifies the investment case for the stock.
Headline Net Income Needs Normalization
Amazon reported $62.6 billion in net income for the second quarter, with $5.75 per diluted share, but the company noted that $53.4 billion of non-operating pre-tax other income, primarily from its investments in Anthropic, was included in the quarter’s results. Therefore, the net income significantly overstates the earnings generated from ongoing customer operations. I place more weight on operating income, AWS profits, and cash generation when analyzing the durability of earnings trends.
This is important when evaluating the company’s valuation because Amazon can report strong trailing earnings due to large non-operating investment gains, but cash flow from those events might not be strong. If investors only focus on headline earnings, Amazon could appear to be cheaper than it really is. Ultimately, the real question is whether operating earnings continue to increase as quickly as to offset the large investments in capital and infrastructure.
AWS Remains the Core Earnings Engine
Approximately 21% of Q2 consolidated revenue came from AWS, and about 60% of segment operating income came from AWS. Because the majority of Amazon’s segment operating income comes from AWS, a slowdown in the growth of the cloud segment could result in a significant decline in Amazon’s equity value. Of course, growth in AI training and inference, as well as cloud based databases and general-purpose compute workloads, should provide a multitude of growth opportunities for Amazon.
That said, Amazon could build out more infrastructure in anticipation of demand and end up with a significant amount of unused capacity. cash returns may lag if the company continues to invest in infrastructure ahead of demand, even if the long-term opportunity is compelling. Therefore, in addition to growth in the AWS business, I would also like to see improving returns on newly built out capacity.
Synopsys Deal Supports Amazon’s Custom-Chip Strategy
On September 30, Synopsys (a provider of semiconductor intellectual property and electronic design automation software) announced a multi-year agreement with Amazon valued at more than $1 billion. According to Synopsys, the agreement expands Amazon’s use of Synopsys silicon IP, EDA, simulation and AI-powered engineering technologies. Synopsys will also use AWS services including EC2 and Amazon Bedrock and work to optimize its software on Trainium and Graviton.
The agreement provides Amazon the ability to build out its chip design infrastructure to support purpose-built chips for cloud and AI workloads. A focus on purpose-built infrastructure may improve Amazon's infrastructure economics to the point where the company can provide customers access to cloud infrastructure at a better price-performance ratio than the competition. Of course, it’s also possible that Amazon may neglect other sources of competitive advantage and focus too much on chips. The agreement does not ensure that Amazon will realize an improvement to its earnings in the near-term, therefore I would consider the agreement to be more of a long-term capability investment by the company rather than a near-term earnings improvement catalyst.
Cash Flow Shows the Cost of Expansion
For the trailing twelve months ending June 30, Amazon reported operating cash flow of $161.4 billion, a 33% increase from the prior year. However, company-defined free cash flow significantly declined to an outflow of $7.6 billion due to a sharp increase in purchases of property and equipment, net of proceeds and incentive payments. This cash outflow is one of the most important elements of the current Amazon story.
Amazon is producing an enormous amount of cash from operations, but Amazon is spending even more on infrastructure. That’s why alternative forms of financing for the AI chips are important. If Amazon can slow the cash outflow from infrastructure without taking onerous long-term obligations, this would strengthen cash flows and benefits shareholders.
Q3 Guidance Sets the Next Fundamental Test
The current Q3 guidance has net sales of between $197 to $202 billion, a 9 to 12% increase from the prior year. Operating income is expected to be between $22.5 to $26.5 billion. Management sets these forecasts and reports results; these will be tested when Amazon reports Q3 results.
The main question I have is if spending on AI-related infrastructure remains elevated, will AWS spending have a sufficient positive impact on operating profits to offset the cash outflow? Investors will also be looking for an improvement in cloud demand. Financing structures that improve the economics, as opposed to merely shifting the costs, would likely strengthen the case for investment.
Amazon Technical Analysis: AMZN Compresses Near $244.58 as Triangle Breakout Approaches
Amazon's most recent close was $248.23 and price has recently compressed between descending resistance and rising support on the 4 hour chart. The defense of the $244.58 support zone has been repetitive, however, buyers continue to struggle with the moving average cluster between $252.61 and $253.57, keeping the stock in a tightening consolidation with a slight bearish bias.
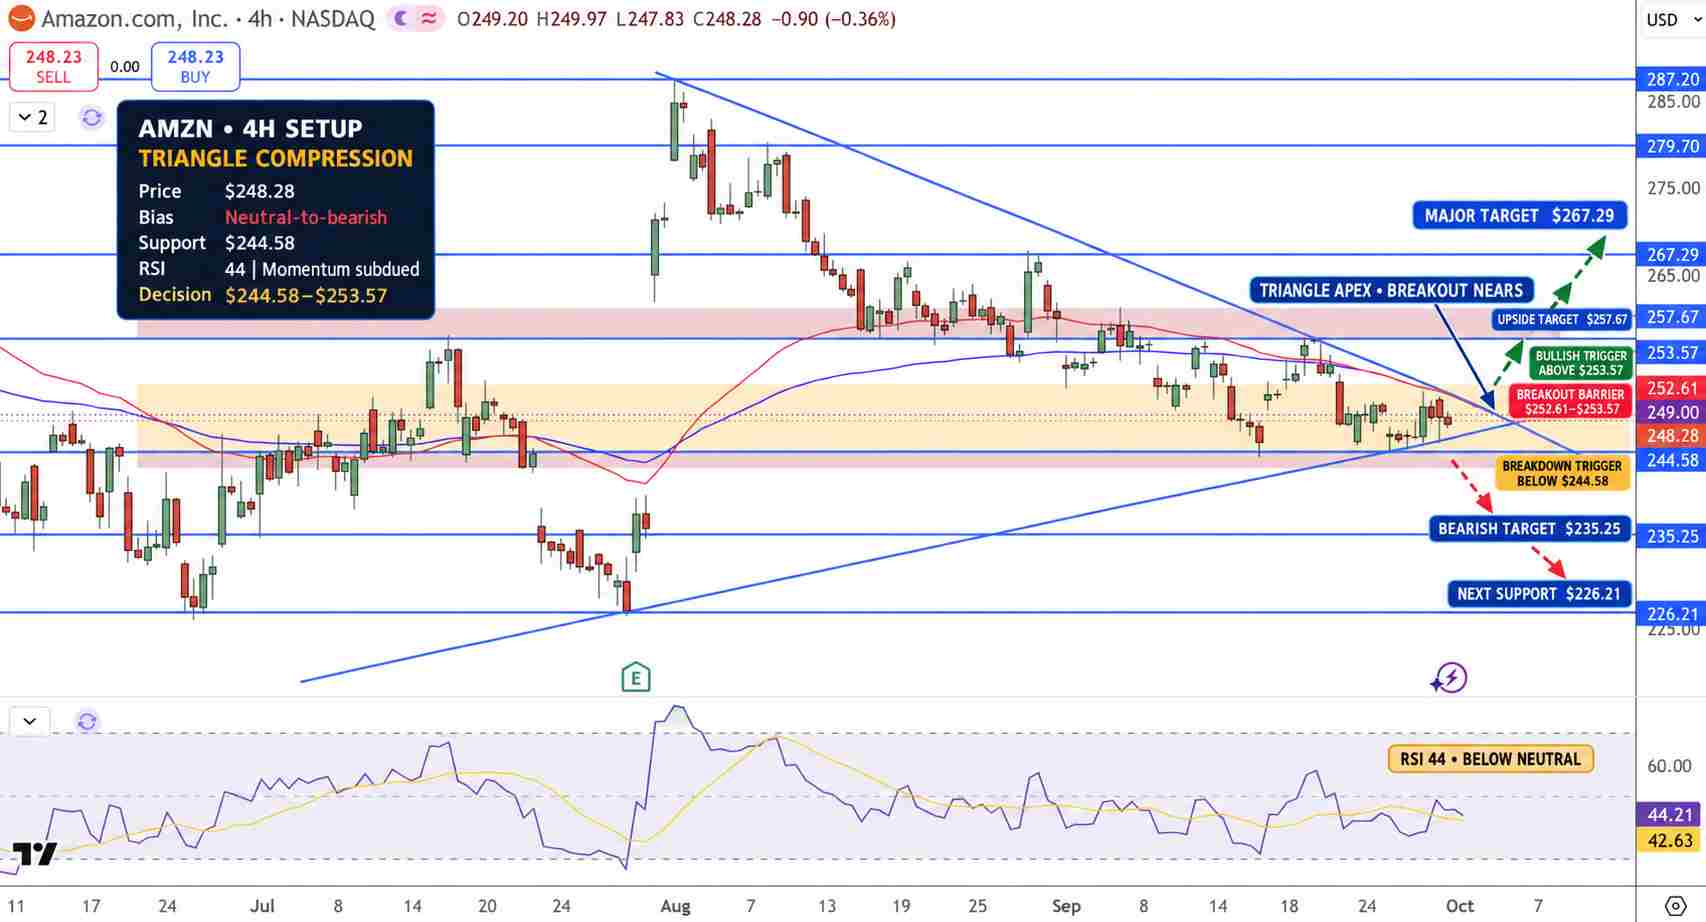
Amazon Stock Price Chart - Source: Tradingview
RSI is around 44, which is above its signal line that is around 43. Although RSI is above the signal line, which is technically bullish, it remains under the neutral 50 level, indicating that the overall market condition is still trending toward bearish. The overall market structure is still in an uneven state and depends on which support/resistance zone is broken.
A 4-hour close below $244.58 and the rising trendline would confirm a break of the bearish triangle and create a bearish structure, with focus on the $235.25, $226.21 levels. A break above $253.57 and the descending resistance would create an improving structure, with focus on the $257.67, $267.29 levels.
I am neutral-to-bearish Amazon's outlook as long as AMZN trades below $253.57. Defense of the $244.58 support level has prevented a stronger bearish call. A close below $244.58 would increase the bearish outlook and shift focus toward the $235.25 area.
Key Levels
• Latest closed price: $248.23
• Important Support Levels: $244.58, $235.25, then $226.21
• Important Resistance Levels: $252.61 to $253.57, $257.67, then $267.29
• RSI: approx. 44, subdued
• Breakout Level: $253.57
• Breakdown Level: $244.58
Why is Amazon stock in focus now?
A new report indicates Amazon is considering moving about $8 billion of Nvidia Grace Blackwell chips into an SPV and leasing them back while the vehicle raises outside financing. The report comes as the pace of spending and growth within Amazon Web Services (AWS) remains strong. The report has investors analyzing whether Amazon can accelerate AI capacity while enhancing the timing and quality of cash returns.
What level confirms a stronger AMZN move?
A 4-hour close above $253.57 would strengthen the level and target $257.67 and $267.29. A close below $244.58 would instead target $235.25.
Bottom Line
AWS and other Amazon operations continue to grow, but the financial case is more about capital allocation. Amazon reported strong cloud growth and operating income in Q2, but free cash flow declined due to accelerating growth in infrastructure spending. The reported proposal to move about $8 billion of Nvidia chips into an investor-backed SPV and lease them back is strategically important; however, the term and the obligations Amazon retains likely impact the economic trade-off.
AMZN is neutral to bearish below $253.57. As long as $244.58 holds, the consolidation remains in place. A close below $244.58 would favor $235.25, and a close above $253.57 would favor $257.67 and $267.29.
Recommended Articles


