




If a Bear Market Is Coming, These Are the 2 Stocks to Avoid -- and the 1 to Own
Key Points
If a bear market is coming, an AI downturn will be a major factor.
Oracle and CoreWeave are both relying on expensive debt to fuel growth, making them vulnerable.
Berkshire Hathaway is built to not just survive market downturns, but use them to its advantage.
- 10 stocks we like better than Berkshire Hathaway ›
It's been quite a ride for investors this year. After an early sell-off, the S&P 500 is up about 21% from its low in March, while the tech-heavy Nasdaq Composite is once again setting records, topping 27,200 just last week.
But a lot is happening all at once. With global instability, elevated oil prices, and bond yields at nearly two-decade highs, some investors are nervous that the recent run will reverse.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If that happens, and a bear market -- a 20% drop in the stock market -- comes, I think a major slowdown in AI spending will play a key part. Here are two stocks I think will fall much further, and one that will fare far better than most.
Oracle's backlog comes with a heavy debt load
On the surface, Oracle (NYSE: ORCL) looks incredible. Sales for its Oracle Cloud Infrastructure (OCI) arm -- the part building and leasing huge AI data centers -- jumped 121% to $7.4 billion in its most recent quarter. The company's remaining performance obligations (RPO) -- contracted revenue for services it hasn't delivered yet -- reached an incredible $664 billion.
But nothing is free, especially in the data center business. Oracle has to actually build the capacity to deliver on those contracts, and that takes a whole lot of cash. Oracle's free cash flow (FCF), the money left over after running the business and paying for things like construction and hardware, was negative $5.4 billion in the latest quarter.
That's a serious shortfall, and it comes even after a program of cost-cutting and significant layoffs.
To fund the difference, Oracle has turned to the debt market. At the end of August, it had $125 billion in long-term debt, plus $288 billion in data-center lease commitments that had not yet begun and aren't yet on its balance sheet.
Oracle is currently spending $1.4 billion every quarter on interest alone. The cash it earns from its operations is $23.1 billion.
While its mix of customers has expanded, Oracle is heavily dependent on a single customer that is, in turn, in a tenuous financial position: OpenAI. The ChatGPT maker is committed to spending $300 billion during the next five years, and as of its latest leaked financials, it had a loss of $12.3 billion last quarter.
That means a serious portion of Oracle's RPO relies on a company that could have trouble paying.
CoreWeave carries the same risks, with less to fall back on
CoreWeave's (NASDAQ: CRWV) issues mirror Oracle's. The difference is in scale, and the fact that if providing AI compute doesn't turn out to be fabulously lucrative, Oracle still has a $24.5 billion software business (and a $15.9 billion cloud applications business). CoreWeave does not.

Image source: Getty Images.
The company is a neocloud, and its entire model -- renting out Nvidia chips to AI customers -- relies on AI to continue booming. If AI demand slips, the company could be in serious trouble.
Of course, CoreWeave's top-line growth is incredible. Just look at the chart below.
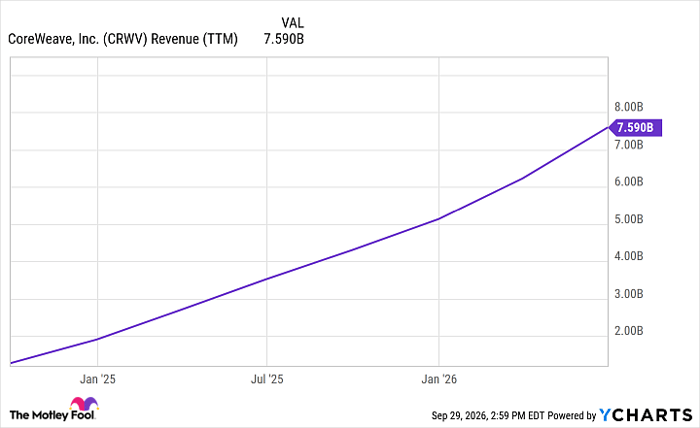
CRWV Revenue (TTM) data by YCharts.
Just as with Oracle, I'm wary of what that growth costs. CoreWeave had $35.6 billion in total debt at the end of June against just $5.5 billion in cash. Interest expense alone was $640 million for the quarter, and just recently, it completed another $4.2 billion convertible debt offering.
Berkshire's cash pile is built for a downturn
Berkshire Hathaway (NYSE: BRKB) (NYSE: BRKA) is absolutely a stock I'd want if things turn south.
Even after the recent departure of legendary Chief Executive Officer Warren Buffett, Berkshire is built to handle major market turmoil -- and profit from it. Berkshire had about $365 billion in cash and U.S. Treasury bills at the end of June. That's capital it can deploy during a market decline, buying good companies at a discount -- exactly what it did during the 2007-2009 financial crisis.
To be fair, the relatively defensive nature of Berkshire has a cost: The stock usually lags behind the market during major rallies. However, the reverse is true during major sell-offs.
Should you buy stock in Berkshire Hathaway right now?
Before you buy stock in Berkshire Hathaway, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Berkshire Hathaway wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $375,240!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,403,292!*
Now, it’s worth noting Stock Advisor’s total average return is 932% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 2, 2026.
Johnny Rice has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Berkshire Hathaway, Nvidia, and Oracle. The Motley Fool has a disclosure policy.
Recommended Articles


