


PepsiCo Stock Forecast: North America Weakness Puts Q3 Earnings in Focus
PepsiCo (PEP) is scheduled to release Q3 earnings on Thursday, October 8, before the bell. The latest close was reported on October 1 at $125.60, down 0.88% from the previous close. The stock has been on a downtrend since early September. The weakness has coincided with uncertainty about the potential for the North American business to improve while management is working to offset the effects of higher costs as well as a more cautious analyst backdrop.
PepsiCo has a solid global business, but domestic weakness is becoming more evident. Q2 results illustrated that international operations could help offset weakness in the U.S., but the stock needs evidence to believe that improving pricing, productivity and portfolio changes would help offset weakness in North America. Therefore, Thursday’s report would help alleviate concerns about longer-term guidance rather than simply affirming that the company is on track to achieve its 2026 goals.
Thursday’s Q3 Earnings Are the Immediate Catalyst
PepsiCo will release third quarter 2026 results on October 8 for the period ended September 5. PepsiCo will file its Form 10-Q, release earnings, and post its prepared remarks at approximately 6:00 a.m. ET. This will be followed by a live webcast of an analyst Q&A at 8:15 a.m. ET with Ramon Laguarta, CEO, and Steve Schmitt, CFO. The author of this article wrote this before PepsiCo's results were released.
The main questions will be whether North American volumes improved and whether management revised its view on the full-year forecast given possible near-term issues (e.g. recovery in the second-half U.S. beverages and snacks, stabilization of pricing actions, and revenue quality, etc.).
PepsiCo ended the second quarter of 2026 upbeat regarding the full-year revenue outlook and core constant-currency EPS growth outlook of 4% to 6% given expectations for continued improvements in demand and revenue mix, plus pricing and cost actions. However, consensus estimates are around 2.30-2.32 in EPS and roughly 25.0-25.2 billion in revenue, implying only modest year-over-year EPS growth. With this in mind, I believe more weight should be given to management's forward-looking commentary.
Wall Street Has Turned More Cautious
In September there was a noticeable change for the worse in the outlook of Wall Street analysts. JPMorgan downgraded PepsiCo from Overweight to Neutral, cutting its price target from $170 to $138. JPMorgan believes the recovery in the U.S. has stalled and the company is now facing greater cost pressure. Deutsche Bank also downgraded the stock to Hold and cut its price target to $138, while TD Cowen cut its price target to $133.
PepsiCo needs to show affordability efforts and greater brand investment are improving the company’s financial performance. Q3 would be a better time to show improvement as international growth has been carrying the company’s recent results. PepsiCo has to show it can get U.S. Frito-Lay back on track.
New Price Increases Test the Affordability Strategy
PepsiCo plans to increase prices on some Doritos and Ruffles as well as some beverages. Prices are expected to increase in the low-to-mid-single digits. Earlier this year, the company reduced prices on some of its snack items by up to approximately 15% to enhance affordability and improve demand with more price-sensitive customers.
The environment has changed, and prices increases are necessary to recoup some of the costs, and possibly help bolster volume. The focus of shareholders has to be on whether PepsiCo is able to raise prices to improve margins without worsening volume and market share for its largest brands.
Q2 Showed Strong Global Growth but Weak North America
PepsiCo released Q2 numbers, including a 6.4% increase in year-over-year net revenues to $24.18 billion, and a 2.4% increase in organic revenues. The company reported a 4% increase in core EPS, which was $2.20, and a 4% increase in core operating profit. Global convenient food organic volume increased 3% and global beverage organic volume increased 2%.
The largest declines were reported in North America. PepsiCo Foods North America (PFNA) reported a 2% decline in revenues and roughly flat organic volume. PepsiCo Beverages North America (PBNA) reported a 4% decline in organic volume. Areas outside North America performed better, including an 9% increase in organic revenues in International Beverages Franchise, 6% increase in Europe Middle East and Africa, and 9% increase in Asia Pacific Foods.
When PepsiCo reports Q3 numbers on October 8, the main focus will be on the performance of PepsiCo Foods North America. The durable recovery will hinge on the return of PepsiCo Foods North America to positive organic volume growth, and less of a negative impact on pricing and margin. The international businesses are performing well, but the stock could remain under pressure if positive consolidated revenue does not alleviate negative North American food volume.
Elliott Pressure Keeps the Turnaround Under Scrutiny
Elliott Investment Management has approximately a $4 billion stake in PepsiCo and has pushed for a more aggressive North American turnaround. As a result, PepsiCo has been reducing costs and product offerings, reviewing its supply chain, focusing on execution in the marketplace, and launching initiatives to make its products less expensive. PepsiCo has said it will remove approximately 20% of its product lines in the U.S. and make changes to its manufacturing and distribution to make it simpler.
Changes to lower costs and make a greater marketplace impact are sensible strategies, but when will the strategies bear fruit? Productivity savings to costs can only protect margins for so long. A true turnaround requires cost reductions in combination with growing demand. This report card is crucial to tell whether changes PepsiCo is implementing following its discussions with Elliott are starting to make a difference.
International Growth Remains a Bright Spot
PepsiCo is continuing its heavy focus on international markets. Late last month, Colombia’s president said that PepsiCo plans to invest $1 billion in Colombia over the next five years. International operations have helped offset declines in PepsiCo’s North American operations.
PepsiCo faces some regulatory risks overseas. PepsiCo and Monster Beverage have challenged a regulation in India that prevents high-caffeine beverages from being labeled as “energy drinks.” PepsiCo has said the regulation affects nearly 500 million bottles and cans of drinks. This example illustrates the various regulations that affect the businesses globally.
Dividend Strength Provides Defensive Support
PepsiCo’s 4.7% dividend yield makes it appealing to investors looking for current income. The dividend also has a defensive nature during times of slower economic growth.
The record dividend increases are also appealing. The longest track record of annual dividend increases is 54 years. However, this track record does not completely alleviate the need for better fundamentals. This would be better achieved with a combination of a stronger yield, expanding margins in North America, and improved North American volumes. The current trend and fundamentals aren’t providing a strong case for the dividend.
Valuation Reflects Lower Expectations
As of October 1, PepsiCo traded at 16.5x TTM and 14.5x forward earnings. Stock Analysis showed a consensus Hold rating with a $151.09 target. The forward multiple suggests a lower growth expectation.
I think valuation is more compelling if the October 8 report confirms 2026 guidance and there is some sign of stabilization of the North America business. Pricing and policy shifts take time to cycle through, and the threat of major disruption to the status quo of 2027 guidance coupled with a return to stiff pricing and restructuring (after 2026) would likely be a concern for the current valuation multiple.
PepsiCo Technical Analysis: PEP Tests $125 as RSI Signals Deeply Oversold Conditions
The October 1 close was $125.60, and PepsiCo continues to trade below both of its major moving averages. It broke a previous rising support and continues to create lower lows and lower highs within a descending channel.
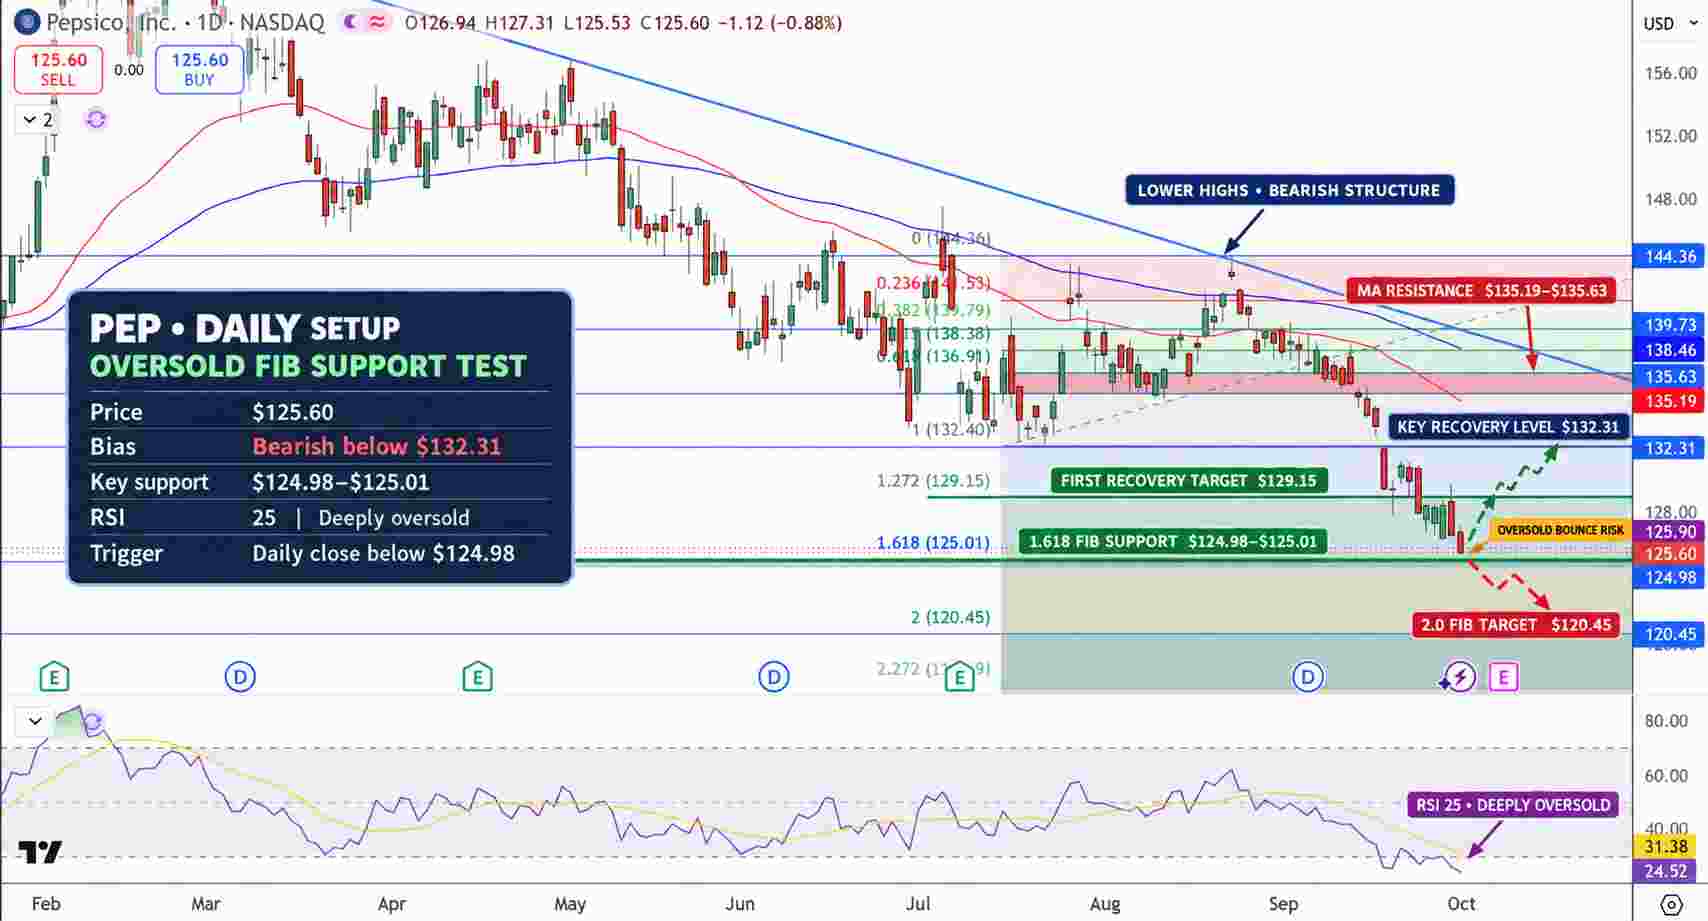
PepsiCo Stock Price Chart - Source: Tradingview
The recent Relative Strength Index (RSI) was around 25, below its signal line around 31. RSI above 70 and below 30 indicate overbought and oversold conditions, respectively. Currently, the RSI suggests a bearish condition. Holding above the $125 support area, however, suggests a short-term bounce may be developing. The 200 day moving average provides a clearer resistance line in the mid to high 130s. In the near term, however, resistance is around $129.15.
The immediate support is $124.98 to $125.01. If this area fails to hold, a bearish structure could be valid and target the $120.45 Fibonacci extension. The first resistance level for bulls would be at $129.15, with the next levels at $132.31 and the large resistance cluster at $135.19 to $135.63.
While I'm bearish as long PEP trades below $132.31, I recognize the RSI is extremely oversold. This makes a move toward $129.15 and $132.31 more likely. A close below $124.98 would make the $120.45 extension more probable.
Key Levels
- Latest completed close available at preparation: $125.60
- Major support levels: $124.98 to $125.01, then $120.45
- Major resistance levels: $129.15, then $132.31, then $135.19 to $135.63
- RSI: approximately 25, deeply oversold
- Recovery trigger: above $132.31
- Breakdown trigger: below $124.98
Why is PepsiCo stock in focus this weekend?
PepsiCo is in focus this weekend because they report Q3 earnings on Thursday, October 8th after a September sell-off and a wave of analyst downgrades due to poor North American trends. Investors will want to see if the company can hold onto its full-year guidance, while showing that the changes it is implementing to alter its portfolio is positively affecting demand for its Frito-Lay and beverage brands.
What level confirms a stronger PEP recovery?
A recovery above $132.31 would be the first significant sign of a short-term bullish trend. A daily close below $124.98 would confirm the bearish trend and open a move towards $120.45.
Bottom Line
The North American turnaround remains the key unresolved issue for PepsiCo. Q2 showed the global business was strong enough to offset the North American business. Price increases and downgrades show the market is losing faith in U.S. volume trends.
The bullish case is dependent on improvements this quarter. Products have already been transitioned, price increases are in place, and cost cuts have been made. Management can show improvements in margins to support the productivity shifts. From a technical analysis, price action gives us a bearish bias below $132.31, and a very oversold condition on the RSI. This makes the $125 area vulnerable to a short-term bounce.
Recommended Articles


