

Dutch Bros Stock Is Down 49% From Its High Despite Revenue Rising 32%. Should You Buy Now or Stay Away?

Source The Motley Fool

Key Points

  • Second-quarter revenue rose 32% year over year, driven by a 5.8% increase in comparable sales.

  • Rising costs and softer comps guidance are weighing on the stock.

  • The stock is trading at an attractive valuation that could set the stage for strong long-term returns.

  • 10 stocks we like better than Dutch Bros ›

Dutch Bros (NYSE: BROS) stock looks like a buy after its recent pullback. The coffee chain posted strong second-quarter results on Aug. 5, with revenue up 32% year over year and healthy margins, but as of Sept. 25, the stock is down 49% from its 52-week high after management's near-term outlook came in softer than investors wanted.

Here's why the market's focus on the third quarter is creating an attractive entry point in this company's long-term growth story.

Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
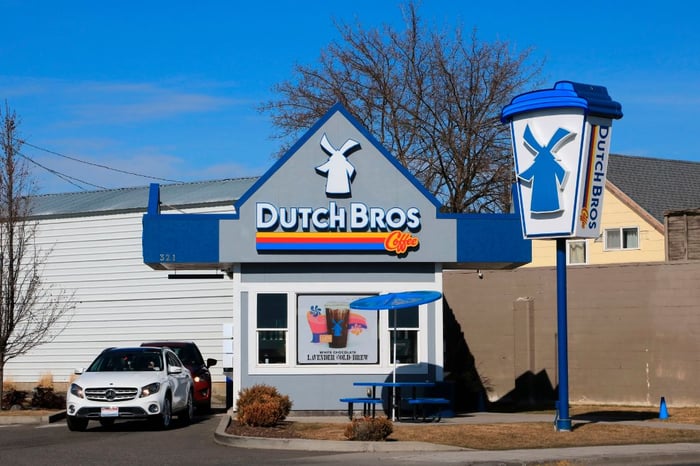
Dutch Bros location

Image source: Getty Images.

Stock sold off on slower comparable sales growth

In the second quarter, Dutch Bros' revenue growth was driven both by 48 new shop openings and 5.8% year-over-year growth in systemwide same-shop sales (a metric that excludes locations opened within the last 15 months). This was the company's 13th straight quarter of same-store sales growth.

Profitability is also improving as the chain scales. On a trailing-12-month basis, net margin reached 7%. In the quarter, net income rose to $51.6 million from $38.4 million a year earlier.

So why did the stock sell off? Four factors stand out:

  1. Third-quarter guidance implied slower momentum. Management expects same-shop sales growth of 4% to 5%. That deceleration in growth reflects that the company faces tougher year-over-year comparisons after last year's food program rollout.
  2. Near-term cost pressures. Higher coffee and food costs, along with a shift toward built-to-suit leases, are expected to raise the cost of goods sold and weigh on the company's gross margin.
  3. Higher capital spending. The company raised its capex guidance to a range of $350 million to $370 million -- up from its prior range of $270 million to $290 million -- as it aims to stay on pace to hit its goal of operating 2,029 shops by 2029.
  4. A deal that didn't happen. On Aug. 5, Dutch Bros said it planned to buy 65 former Salad and Go locations, but later walked away after a competing bid exceeded its maximum price.

Wall Street prefers a clean, predictable growth path. When anything clouds a company's near-term outlook -- even if its long-term narrative is intact -- the market often punishes the stock.

But the opportunity hasn't changed. At its March 2025 investor day, management pegged its long-term U.S. expansion potential at over 7,000 shops. With 1,225 locations open as of June 30, 2026, Dutch Bros still has a long runway for growth ahead.

Dutch Bros is trading at 2.6 times sales

The rising profit margin and the discipline to avoid overpaying for Salad and Go suggest management is prioritizing profitable growth and long-term shareholder returns. The stock's near-term volatility has created an opening for long-term investors to buy in at a lower valuation.

Dutch Bros trades at about 2.6 times sales. Restaurant chains like Starbucks and Chipotle often commanded price-to-sales multiples in the 3 to 4 range during their early-stage, high-growth years, so 2.6 is a clear discount. For investors who can hold the stock for at least five years, Dutch Bros looks like a buy on this pullback.

Should you buy stock in Dutch Bros right now?

Before you buy stock in Dutch Bros, consider this:

The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Dutch Bros wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.

Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $383,680!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,382,954!*

Now, it’s worth noting Stock Advisor’s total average return is 937% — a market-crushing outperformance compared to 214% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.

See the 10 stocks »

*Stock Advisor returns as of September 29, 2026.

John Ballard has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Chipotle Mexican Grill, Dutch Bros, and Starbucks. The Motley Fool recommends the following options: short September 2026 $35 calls on Chipotle Mexican Grill. The Motley Fool has a disclosure policy.

Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
Gold ends three-week slide at the $4,400 line — eight straight days of ETF inflows vs a 5% 10-year and a 100 dollarSpot gold closed Friday at $4,378.39, up 0.84% on the day and about 0.8% for the week — its first weekly gain in four weeks — with the intraday high of $4,399.67 leaving it 33 cents shy of the $4,400 line. Gold ETFs have now logged eight straight sessions of inflows, but with the 10-year back above 5% and the dollar index near 100, here is what decides whether this is a reversal or a bounce.
Author  Suzie
Sep 20, Sun
Spot gold closed Friday at $4,378.39, up 0.84% on the day and about 0.8% for the week — its first weekly gain in four weeks — with the intraday high of $4,399.67 leaving it 33 cents shy of the $4,400 line. Gold ETFs have now logged eight straight sessions of inflows, but with the 10-year back above 5% and the dollar index near 100, here is what decides whether this is a reversal or a bounce.
placeholder
October hike odds climb toward 60% as Goldman and BofA both flip — what Warsh's "dose of accommodation" really changedRate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
Author  Irene Q.
Sep 23, Wed
Rate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
placeholder
Four jobs reports in five days: what JOLTS, ADP, claims and the September payrolls mean for the October Fed decisionThe US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
Author  Mitrade
Yesterday 06: 33
The US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
placeholder
Nvidia's $150 billion buyback landed — and the AI sector fell anyway. That's the signal worth tradingNvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
Author  Irene Q.
8 hours ago
Nvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
placeholder
The 30-year Treasury just hit a 22-year high — and the bond market is not pricing the Fed, it is pricing the deficitThe 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
Author  Irene Q.
7 hours ago
The 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
goTop
quote