

Natural Gas - Futures (NATGAS-F) Volatility Intensified on Sep 29: What to Watch

Source Tradingkey

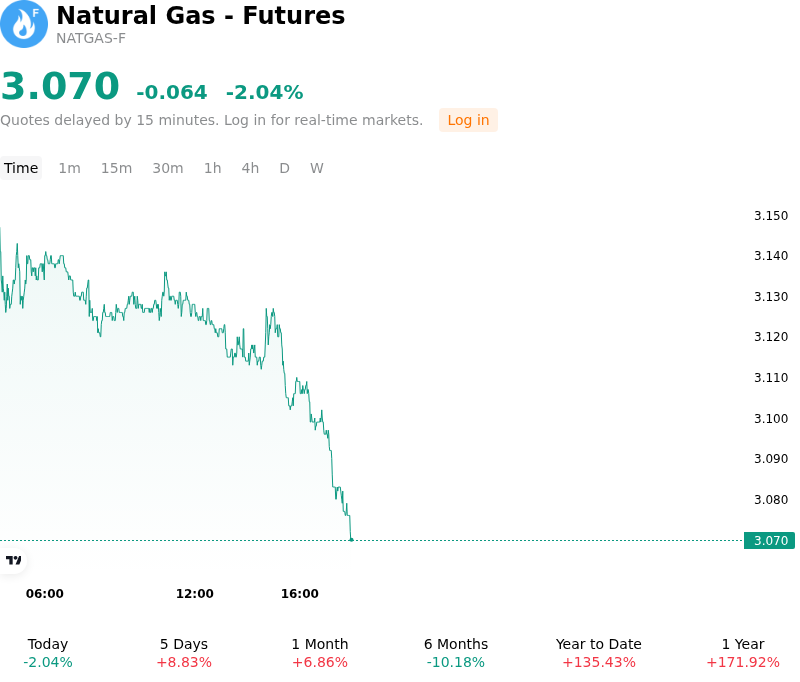
Natural Gas - Futures (NATGAS-F) is down 2.04% at Sep 29 05:45(ET), now at $3.07, with a 7-day up of 1.96%.
SummaryOverview

What is driving Natural Gas - Futures (NATGAS-F)’s stock price down today?

The decline in natural gas futures was primarily driven by easing supply concerns following the prompt resolution of regional pipeline disruptions in Appalachia. The lifting of a force majeure on TC Energy's Columbia Gas Transmission system restored previously bottlenecked regional flows, signaling to market participants that Marcellus and Utica shale production would rapidly reintegrate into Lower 48 supply streams. This rapid restoration of transportation capacity removed the short-term supply risk premium that had temporarily elevated near-term contract pricing.

Compounding the downside momentum is the broader transition into autumn shoulder-season demand weakness across key consuming regions. Moderate weather patterns across major population centers have drastically reduced cooling degree days, curbing power-sector natural gas consumption for air conditioning while heating demand has yet to materialize. Concurrently, seasonal maintenance at several major U.S. liquefied natural gas export facilities has temporarily constrained feedgas intake. This reduction in export volume has diverted additional daily production into the domestic market, further depressing spot and near-curve prices.

From a market balance perspective, these demand headwinds coincide with robust domestic production hovering near record levels. The combination of strong dry gas output and muted physical consumption continues to support steady underground storage injections, keeping working gas inventories comfortably capitalized above historical five-year averages ahead of the winter heating season. In response, institutional market participants liquidated short-term bullish positions and trimmed winter risk premiums, reflecting an expectations framework anchored by an amply supplied physical market.

Technical Analysis of Natural Gas - Futures (NATGAS-F)

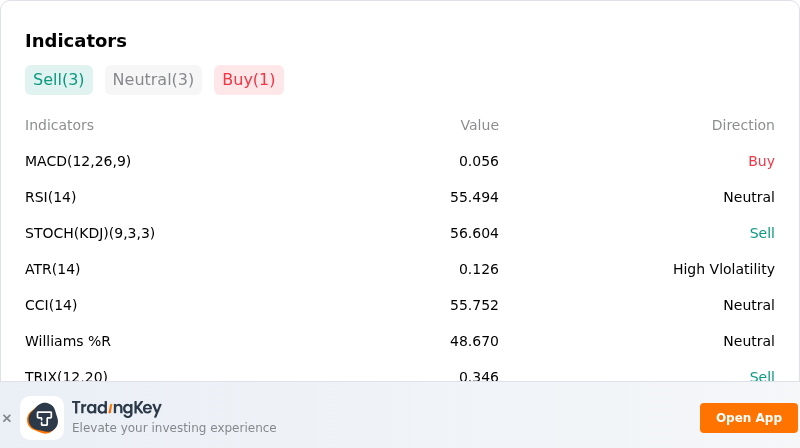
Technically, Natural Gas - Futures (NATGAS-F) shows a MACD (12,26,9) value of 0.056, indicating a buy signal. The RSI at 55.494 suggests neutral condition and the Williams %R at 48.670 suggests neutral condition. Please monitor closely.
IndicatorAnalysis

More details about Natural Gas - Futures (NATGAS-F)

Recent Events and Risks:

  • Unwinding Supply Outage Premium: Columbia Gas Transmission lifted its force majeure on the Mountaineer XPress pipeline in West Virginia, reinstating up to 1.8 Bcf/d of Appalachian transport capacity and triggering profit-taking and long liquidation as regional bottleneck fears vanished.
  • Mild Shoulder-Season Weather Demand: Near-term 15-day forecasts across the Lower 48 project moderate temperatures, suppressing residential space-heating demand before winter while summer power-burn cooling load dissipates, driving national gas consumption to a seasonal low.
  • LNG Feedgas Intake Curtailments: Scheduled annual maintenance at Maryland's Cove Point LNG terminal and temporary flow reductions at Gulf Coast facilities capped total U.S. LNG export feedgas nominations near 18 Bcf/d, leaving excess volume stranded in domestic pipelines.
  • Accelerating Pre-Winter Inventory Builds: Upcoming weekly storage reports are expected to show large autumn injections ranging between 80 Bcf and 90 Bcf, threatening to push total U.S. working gas inventories near 3,900 Bcf before winter and reinforcing an ample supply cushion over historical norms.
Disclaimer: For information purposes only. Past performance is not indicative of future results.
placeholder
October hike odds climb toward 60% as Goldman and BofA both flip — what Warsh's "dose of accommodation" really changedRate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
Author  Irene Q.
Sep 23, Wed
Rate futures now price roughly 55% to 62% for a 25bp hike at the October 27-28 FOMC, up from about 30% before Chair Warsh's post-meeting framing that the Fed is merely "removing some accommodation." Goldman Sachs has added an October hike to its forecast and Bank of America now sees moves in both October and December. Here is the repricing, the language behind it, and the two data points that decide it.
placeholder
Four jobs reports in five days: what JOLTS, ADP, claims and the September payrolls mean for the October Fed decisionThe US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
Author  Mitrade
Sep 28, Mon
The US labour market faces its densest data week of the month. JOLTS job openings land Tuesday (7.2 million expected), ADP on Wednesday (70,000 expected), initial claims on Thursday and the September non-farm payrolls on Friday (100,000 expected, down from 162,000). Markets price a 64%-70% chance of another quarter-point Fed hike on October 28. The dollar index sits at 100.77 and the S&P 500 at 7,729.8.
placeholder
RBA set to hike interest rate to 4.60% in September as inflation remains elevatedThe Reserve Bank of Australia (RBA) is widely expected to raise the Official Cash Rate (OCR) by 25 basis points (bps) to 4.60% from 4.35% on Tuesday, after keeping rates unchanged at its previous two meetings
Author  FXStreet
Yesterday 01: 40
The Reserve Bank of Australia (RBA) is widely expected to raise the Official Cash Rate (OCR) by 25 basis points (bps) to 4.60% from 4.35% on Tuesday, after keeping rates unchanged at its previous two meetings
placeholder
Nvidia's $150 billion buyback landed — and the AI sector fell anyway. That's the signal worth tradingNvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
Author  Irene Q.
22 hours ago
Nvidia closed up 1.68% at $228.86 on 28 September after announcing a $150 billion share repurchase authorisation, the largest single corporate buyback on record, while the rest of the AI complex sold off: AMD -3.6%, Micron -2.6%, Meta -4.8% and the Philadelphia Semiconductor Index -1.61%. The divergence is not noise. Capital is rotating toward cash-flow certainty, not abandoning the AI theme. With Micron reporting after the close on 30 September, here is what the split means.
placeholder
The 30-year Treasury just hit a 22-year high — and the bond market is not pricing the Fed, it is pricing the deficitThe 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
Author  Irene Q.
21 hours ago
The 30-year Treasury yield closed at 5.56% on 28 September, the highest since June 2004, while the 10-year reached 5.24% and the 20-year 5.60%. The curve has steepened roughly 30bp in eight sessions even as October hike odds sit at 70.3%. That gap is the story: the long end is repricing fiscal and inflation risk, not policy. With PCE on Wednesday and payrolls on Friday, here is what the long end is really saying.
goTop
quote