




Jensen Huang Maintained His Prediction That AI Infrastructure Spending Will Hit $3 Trillion to $4 Trillion by 2030 -- the Same Forecast He Made a Year Ago to the Day. Is Nvidia Still a Buy at These Levels?
Key Points
Nvidia doesn't just sell GPUs -- it also builds entire supercomputers for hyperscaler clients.
It's investing in other companies, many of which are committed to buying its products.
Nvidia stock trades at an attractive valuation.
- 10 stocks we like better than Nvidia ›
Jensen Huang is the CEO of Nvidia (NASDAQ: NVDA), and he frequently speaks about advances in artificial intelligence (AI). He has a knack for simplifying complex ideas, and he doesn't shy away from making bold predictions.
Last year, he projected that global AI infrastructure spending would reach $3 trillion to $4 trillion in 2030. He doubled down on that projection at the Goldman Sachs Communacopia + Technology Conference last week, saying, "I just think we should just take a pause and acknowledge that I was right."
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
As AI development continues at a rapid pace, Nvidia is poised to benefit, but is there room for the stock to move higher?
Nvidia is more than a chip company
For many years, Nvidia was a relatively obscure company designing chips mostly for the video game industry. Its graphics processing units (GPUs) provide the high-speed parallel processing power that's necessary to render high-level graphics in real time.
Nvidia CEO Jensen Huang. Image source: Nvidia.
Those same attributes make the chips ideal for handling the computationally heavy workloads of artificial intelligence development and inference.
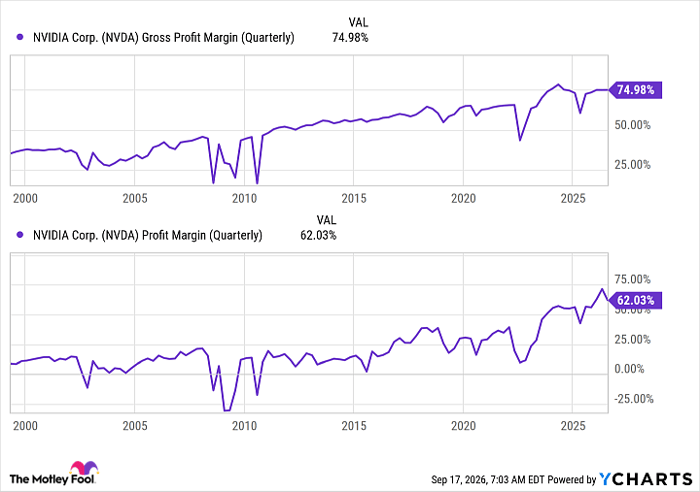
After generative AI was introduced to the world through OpenAI's ChatGPT almost four years ago, Nvidia quickly became a household name, increasing more than tenfold in size to become the most valuable company in the world. Nvidia's revenue has increased more than 1,000% over that time, and it's also become a much more efficient company, with expanding margins.
NVDA Gross Profit Margin (Quarterly) data by YCharts.
In the process, it has become a much different company, and although GPUs are still its core business, it would be a mistake to overlook the other areas in its business.
For starters, rather than selling only chips, it's increasingly selling entire computing systems. Its newest platform is called Vera Rubin, a multirack supercomputer that includes Vera central processing units (CPUs) and Rubin GPUs. Nvidia's hyperscaler clients are already invested in these systems, which creates high barriers to entry for the chipmaker's competitors. It isn't as simple as switching chips.
Nvidia's increasingly investing in other companies, which opens up other revenue streams and increases its profits as these investments grow. Some of its relationships are mutually beneficial: Nvidia provides seed money, and the partner commits to buying Nvidia products. The most well-known example of these relationships is probably the one it has with CoreWeave. Nvidia has invested more than $2 billion into the neocloud, which is buying large quantities of Nvidia chips to power its data centers.
Nvidia also recently acquired large language model (LLM) platform Hugging Face for $12.9 billion, expanding its operations into new markets.
This all makes it likely that Nvidia will continue to benefit in a big way as AI spending heads toward $4 trillion.
Nvidia is still growing fast
It's rare for a company that's already massive to keep growing as rapidly as Nvidia is. Its revenue increased 106% year over year in its fiscal 2027 second quarter (which ended July 26), and management has already issued guidance forecasting 70% growth in its fiscal 2028.
Normally, a performance like that would lead to a huge stock jump. However, that might not happen here. The market already took Huang's 2030 projection into account last year. As Nvidia reaches its goals, some of the expected growth is already built into the price.
Objectively, Nvidia stock isn't expensive, trading at a price-to-earnings (P/E) ratio of 27. Considering its expanding addressable market, dominance in a growing industry, and attractive price, I do think it's still a buy at these levels.
Should you buy stock in Nvidia right now?
Before you buy stock in Nvidia, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Nvidia wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $406,141!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,347,745!*
Now, it’s worth noting Stock Advisor’s total average return is 940% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 18, 2026.
Jennifer Saibil has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Goldman Sachs Group and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


