


SpaceX Burned More Than $9.9 Billion of Free Cash Flow in a Single Quarter. Here's How Long Its $85.7 Billion IPO War Chest Actually Lasts.
Key Points
Space Exploration Technologies is growing quickly but burning a lot of cash in the process.
It has a complicated business plan that relies on major engineering breakthroughs in a short time frame.
Elon Musk is promising massive revenue gains, but these goals are likely too lofty, even for SpaceX.
- 10 stocks we like better than Space Exploration Technologies ›
Space Exploration Technologies (NASDAQ: SPCX) is perhaps the most ambitious company in history. The rocket launch company that just went public in the largest initial public offering (IPO) ever, raising $85.7 billion in the process, is also trying to tackle artificial intelligence (AI) infrastructure, satellite internet, and even semiconductor fabrication.
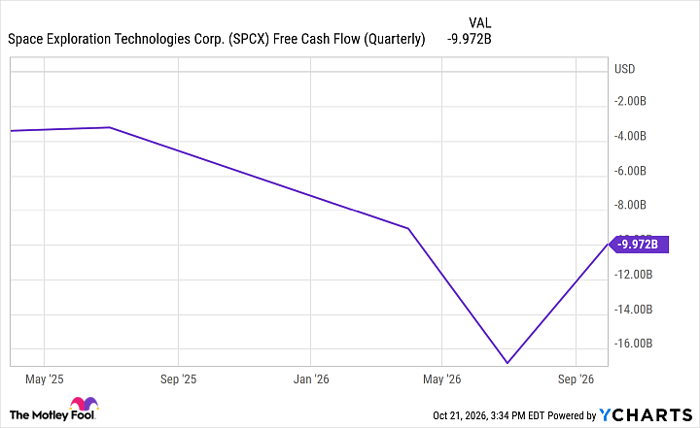
SpaceX just reported second-quarter earnings, burning $9.9 billion in free cash flow due to its massive capital spending plans. Management has called for even more aggressive spending in the quarters ahead. Here's what that means for SpaceX's AI business, how long its IPO proceeds will last before it needs to raise more funds, and whether the stock is a buy today.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Fast growth, faster capital spending
To take advantage of the opportunity afforded by the AI spending boom, SpaceX has built a data center business, along with its own AI software tools, such as its recent acquisition, Cursor, as well as Grok Bot. It has smartly brought on data centers in a supply crunch, leading big customers like Alphabet and Anthropic to flock to it for contracts.
Last quarter, ending in September, SpaceX's AI infrastructure revenue was $7 billion, up from a measly $359 million a year prior, driven by large contracts signed in 2026. However, to achieve this strong revenue growth, SpaceX is incurring heavy capital expenditures, resulting in a negative free cash flow of $9.9 billion for the period.
Total capital expenditures of $19.5 billion in Q3 are expected to double sequentially to around $40 billion, putting SpaceX's capital spending in the same ballpark as hyperscalers like Microsoft. It is going from a standing start at an extremely aggressive pace to try and become a major player in AI infrastructure, and so far, it is paying off with rapid revenue growth.
SpaceX will eventually need to generate positive free cash flow, as the funds from the IPO will run out within two years at the current burn rate. Management should be able to raise funds if this rapid growth continues, but it is always better to bet on a rock-solid business model that generates positive free cash flow than to hope a company can keep raising capital.
Image source: Getty Images.
A complicated story that needs to be woven together
SpaceX's business plan is ambitious and will be difficult to execute. That's not to say it hasn't pulled off miracles before, but this time there is a lot on its plate to achieve positive free cash flow within the next few years.
One, the Starship ayloads to orbit. When it does, SpaceX plans to launch a bunch of new advanced satellites for its Starlink internet service, along with orbital data centers for its AI infrastructure business. It is also working on its own semiconductor manufacturing hub in conjunction with Tesla, another technology giant owned by Elon Musk, with which SpaceX is considering a merger.
All this has Elon Musk betting that SpaceX will achieve annual recurring revenue (ARR) of $500 billion to $1 trillion by the end of 2027, which is barely a year from now. Taking its overall quarterly revenue in Q3, its ARR was $58.3 billion. That means around a 10x increase in its quarterly revenue by Q4 of next year, a goal that is likely not achievable in such a short time frame.
SPCX Free Cash Flow (Quarterly) data by YCharts.
Should you buy SpaceX despite its cash burn?
Investors are rewarding SpaceX for burning cash to accelerate revenue growth as it invests in AI data centers. It now has a market cap of $2.15 trillion.
Unless you believe Musk's claims that ARR will reach $500 billion or more by this time next year, SpaceX stock is likely overvalued and very risky to buy, given its heavy cash burn. It currently trades at a price-to-sales ratio (P/S) of 69, which is one of the most expensive sales ratios in the stock market today.
Sure, it is one of the fastest-growing businesses, but who's to say when the AI spending boom will slow down? That would be detrimental to SpaceX's share price.
For all these reasons, it is probably best to avoid buying SpaceX stock right now.
Should you buy stock in Space Exploration Technologies right now?
Before you buy stock in Space Exploration Technologies, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Space Exploration Technologies wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $361,596!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,303,935!*
Now, it’s worth noting Stock Advisor’s total average return is 910% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 23, 2026.
Brett Schafer has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Alphabet, Microsoft, and Tesla. The Motley Fool has a disclosure policy.
Recommended Articles


