


Oil Companies Enter 2027 With Their Strongest Balance Sheets in Years. Here's What to Expect Next Year.
Key Points
The energy sector is known for volatility, with oil prices swinging between high and low levels.
The world's largest energy companies build financially strong businesses to weather the swings.
Even the balance sheets of smaller, pure-play drillers are benefiting from high oil prices.
- 10 stocks we like better than Chevron ›
Oil is a volatile commodity, a fact you have to accept if you are going to buy an energy stock like Chevron (NYSE: CVX), ExxonMobil (NYSE: XOM), Devon Energy (NYSE: DVN), or Diamondback Energy (NASDAQ: FANG). However, oil volatility can be both a negative and a positive. Right now, high oil prices are helping to strengthen energy company balance sheets. Here's what that means for investors in 2027.
Oil goes up, and oil goes down
In 2020, during the coronavirus pandemic, oil prices cratered amid the economic shutdown used to slow the spread of the illness. It was a difficult time for the world, but energy companies were particularly hard hit. At one point, oil prices in the United States fell below zero. There were technical reasons for the brief and shocking decline, but it shows just how difficult a period it was for energy companies.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Getty Images.
To support their businesses during that period, oil companies across the industry drew on their balance sheets. Drilling focused Devon Energy's debt-to-equity ratio doubled in 2020. Peer Diamondback Energy's debt-to-equity ratio increased by nearly 80% before peaking in early 2021. And Exxon and Chevron, two of the world's largest and most diversified energy companies, saw their debt-to-equity ratios increase by roughly 70% in 2020.
But today, with oil prices at lofty levels, the story is completely different. Debt-to-equity ratios are the lowest they have been in years. Exxon and Chevron are both below 0.2x, which would be a strong number for any business. Devon is slightly below 0.3x, and Diamondback Energy is just a touch above. These companies, and many more in the energy patch, are in a very strong financial position.
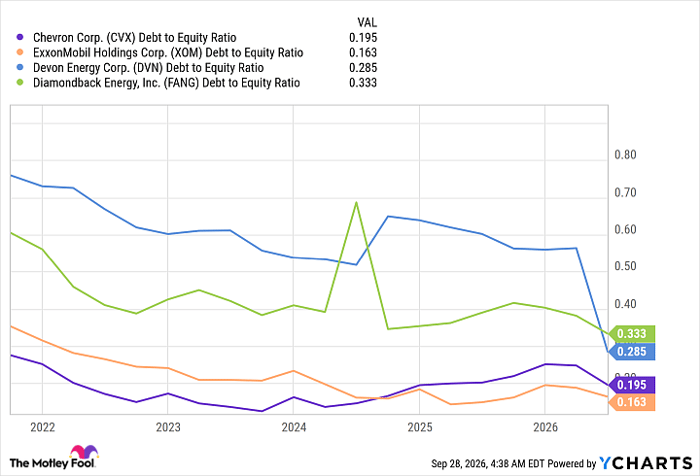
CVX Debt to Equity Ratio data by YCharts
What will energy companies do with their strong balance sheets?
For companies like Exxon and Chevron, the current strength of their balance sheets won't really change their business approach. They both focus on the long-term. They may increase stock buybacks and, perhaps, pull forward some capital investment plans, but they understand the volatility of energy prices.
Soon enough, they are likely to need to deal with low oil prices again. When that happens, having strong balance sheets will allow Exxon and Chevron to both support their businesses and dividends through the downturn. Notably, Exxon's dividend has been increased annually for 43 years, with Chevron's streak at 38 years. For income-focused investors looking for direct oil exposure, either one would be a great choice, though Chevron has the higher yield right now at 3.5%. Exxon's yield is 2.6%.
Devon Energy and Diamondback Energy probably require a bit more watching. These two U.S.-based energy producers have long and successful operating histories, so it is unlikely they will do anything rash. However, the extra cash they are generating today may be used to increase production to capitalize on the current price environment. Acquisitions could also be in the cards. However, both have a history of paying out special dividends during periods of elevated oil prices, with the goal of sharing their success with shareholders. In recent years, deleveraging has been a greater focus, but as leverage has fallen, that capital allocation framework may shift back toward returning cash to shareholders. That could also take the form of stock buybacks, so investors probably shouldn't get their hopes up on the dividend front.
This energy swing is entirely normal
The big picture here is that high oil prices are likely to be temporary, and energy companies know it. The first thing an energy company does in this situation is often to strengthen the balance sheet. But that's largely in preparation for the next oil downturn, which may come before the company has a chance to do anything else with the cash it is generating. While acquisitions, rising dividends, and increased stock buybacks may follow along for the ride, those aren't things that you can really count on.
So the real takeaway here is that oil companies like Exxon, Chevron, Devon, and Diamondback, with increasingly strong balance sheets, will enter 2027 with the financial strength needed to survive the next energy downturn. Anything after that is really icing on the cake.
Should you buy stock in Chevron right now?
Before you buy stock in Chevron, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Chevron wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $383,680!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,382,954!*
Now, it’s worth noting Stock Advisor’s total average return is 937% — a market-crushing outperformance compared to 214% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 28, 2026.
Reuben Gregg Brewer has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Chevron. The Motley Fool has a disclosure policy.
Recommended Articles


