


US S&P Global PMI expected to signal slower business activity in October
- US business activity is expected to slow slightly in October, while remaining firmly in expansion territory.
- Manufacturing and services surveys are forecast to ease, following strong readings in September.
- The US Dollar could find support if stronger-than-expected business activity reinforces expectations of further Fed rate hikes.
The United States (US) S&P Global preliminary Purchasing Managers Indices (PMIs) for October will be released on Friday, providing fresh insights into the health of the world's largest economy ahead of next week's Federal Reserve (Fed) monetary policy meeting.
The report includes the Manufacturing PMI, Services PMI and Composite PMI, which measure business activity across the private sector. Readings above 50 indicate expansion, while figures below that threshold signal contraction.
The October surveys come at a time when recent US economic data continue to highlight resilient economic activity, despite persistent inflationary pressures and elevated borrowing costs. Investors will closely monitor the figures for signs of slowing growth and renewed price pressures that could influence the Fed's monetary policy outlook and the US Dollar (USD).
What can we expect from the October S&P Global PMI report?
Market expectations point to a moderate slowdown in US private-sector activity in October, following particularly strong readings in September. The S&P Global Manufacturing PMI is expected to decline slightly to 55.6 from 55.9 in September, while the Services PMI is forecast to ease to 57.9 from 58.8. Meanwhile, the Composite PMI stood at 58.4 in September, highlighting robust growth across the US private sector.
Although both sectors are expected to lose some momentum, the anticipated figures remain comfortably above the 50 threshold, suggesting that the US economy continues to expand at a healthy pace.
The report will be particularly important given the latest signs of persistent inflationary pressures. Recent US economic releases show stronger-than-expected inflation, while Retail Sales and labor market indicators continue to suggest that domestic demand remains resilient.
Against this backdrop, the Fed is widely expected to leave interest rates unchanged at its October 28 meeting, following a 25-basis-point (bps) increase in September. However, investors are fully pricing in another rate hike in December, according to the CME FedWatch tool.
When will the October flash US S&P Global PMIs be released, and how could they affect EUR/USD?
The S&P Global Manufacturing, Services and Composite PMIs for October will be released on Friday at 13:45 GMT. The publication could trigger volatility in the US Dollar and the EUR/USD pair, particularly as investors position themselves ahead of the Fed's October 28 monetary policy decision.
A stronger-than-expected report could reinforce expectations of additional Fed rate hikes in the coming months. Such a scenario would likely support US Treasury yields and the US Dollar, potentially weighing on EUR/USD.
Conversely, a sharper-than-anticipated slowdown in business activity, particularly in the services sector, could raise concerns about the sustainability of US economic growth. Weaker PMI readings could encourage investors to reassess the likelihood of further monetary tightening, putting downward pressure on the Greenback and supporting EUR/USD.
However, the market reaction could remain relatively limited if the figures broadly match expectations, given that both manufacturing and services activity are forecast to remain firmly in expansion territory.
With another Fed rate hike already largely priced in for December, investors will closely assess whether Friday's PMI figures confirm the resilience of the US economy or point to a slowdown. A stronger-than-expected report could reinforce expectations of further monetary tightening, while disappointing readings could cast doubt on the strength of economic growth and weigh on the US Dollar.
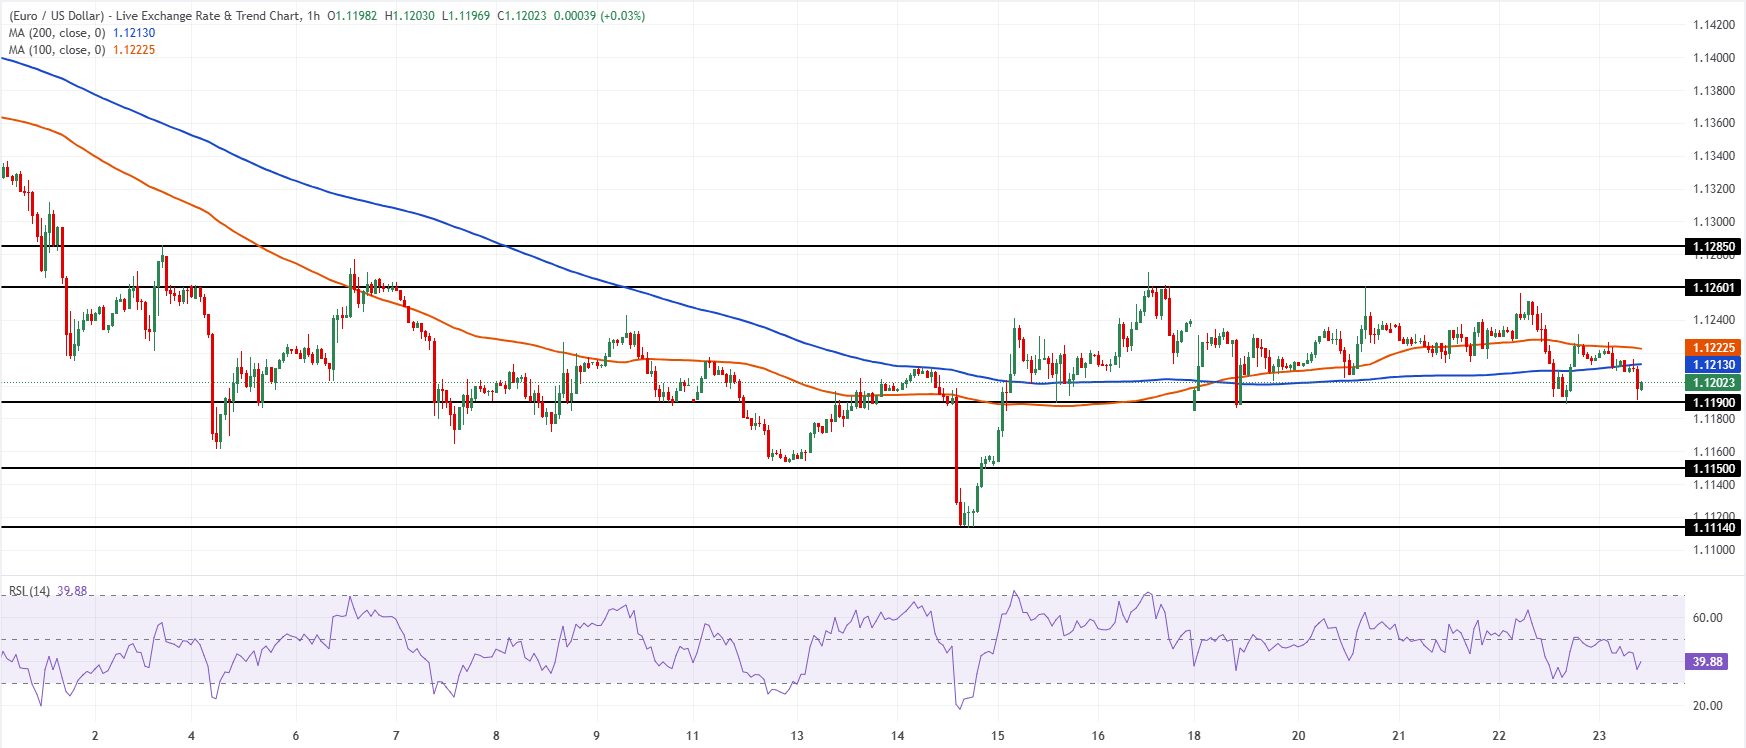
EUR/USD remains modestly bearish on the one-hour chart, holding below the 100-period Simple Moving Average (SMA) at 1.1223 and the 200-period SMA at 1.1213. The pair is drifting just above nearby price support, while the Relative Strength Index (14) around 40 hints at waning bullish momentum rather than outright oversold conditions, suggesting downside risks remain while these averages cap the topside.
On the downside, initial support emerges at the horizontal level near 1.1190, ahead of deeper floors at 1.1150 and 1.1114. On the topside, immediate resistance is seen at the 200-period SMA at 1.1213, followed by the 100-period SMA at 1.1223, with stronger hurdles at 1.1260 and 1.1285 that would need to be reclaimed to ease the current bearish bias.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar FAQs
The US Dollar (USD) is the official currency of the United States of America, and the ‘de facto’ currency of a significant number of other countries where it is found in circulation alongside local notes. It is the most heavily traded currency in the world, accounting for over 88% of all global foreign exchange turnover, or an average of $6.6 trillion in transactions per day, according to data from 2022. Following the second world war, the USD took over from the British Pound as the world’s reserve currency. For most of its history, the US Dollar was backed by Gold, until the Bretton Woods Agreement in 1971 when the Gold Standard went away.
The most important single factor impacting on the value of the US Dollar is monetary policy, which is shaped by the Federal Reserve (Fed). The Fed has two mandates: to achieve price stability (control inflation) and foster full employment. Its primary tool to achieve these two goals is by adjusting interest rates. When prices are rising too quickly and inflation is above the Fed’s 2% target, the Fed will raise rates, which helps the USD value. When inflation falls below 2% or the Unemployment Rate is too high, the Fed may lower interest rates, which weighs on the Greenback.
In extreme situations, the Federal Reserve can also print more Dollars and enact quantitative easing (QE). QE is the process by which the Fed substantially increases the flow of credit in a stuck financial system. It is a non-standard policy measure used when credit has dried up because banks will not lend to each other (out of the fear of counterparty default). It is a last resort when simply lowering interest rates is unlikely to achieve the necessary result. It was the Fed’s weapon of choice to combat the credit crunch that occurred during the Great Financial Crisis in 2008. It involves the Fed printing more Dollars and using them to buy US government bonds predominantly from financial institutions. QE usually leads to a weaker US Dollar.
Quantitative tightening (QT) is the reverse process whereby the Federal Reserve stops buying bonds from financial institutions and does not reinvest the principal from the bonds it holds maturing in new purchases. It is usually positive for the US Dollar.
Economic Indicator
S&P Global Composite PMI
The S&P Global Composite Purchasing Managers Index (PMI), released on a monthly basis, is a leading indicator gauging US private-business activity in the manufacturing and services sector. The data is derived from surveys to senior executives. Each response is weighted according to the size of the company and its contribution to total manufacturing or services output accounted for by the sub-sector to which that company belongs. Survey responses reflect the change, if any, in the current month compared to the previous month and can anticipate changing trends in official data series such as Gross Domestic Product (GDP), industrial production, employment and inflation. The index varies between 0 and 100, with levels of 50.0 signaling no change over the previous month. A reading above 50 indicates that the private economy is generally expanding, a bullish sign for the US Dollar (USD). Meanwhile, a reading below 50 signals that activity is generally declining, which is seen as bearish for USD.
Read more.Next release: Fri Oct 23, 2026 13:45 (Prel)
Frequency: Monthly
Consensus: -
Previous: 58.4
Source: S&P Global
Recommended Articles


