


Micron Just Revealed a New Business Strategy. That Change Makes It a Screaming Buy.
Key Points
Micron's stock is dirt cheap because the market is still worried about a downturn.
Micron is taking steps to stabilize its business.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Micron (NASDAQ: MU) is changing its business. Since the start, Micron has made memory chips, and their prices are dictated by market demand. When times are good (like they are now), Micron can make a fortune. When times are bad, Micron's business looks helpless. However, Micron is using today's memory chip demand wave to reform its business.
I think this shift makes Micron a different stock than it has historically been viewed as, making it a no-brainer buy today.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
Micron is moving toward contract-based revenue
Because all available production capacity has been consumed by AI companies building data centers, supply is scarce. This has caused memory chip prices to rise, and those building out data centers are feeling the heat. However, Micron may not care a lot. Previously, Micron's clients would buy memory chips as needed, leaving Micron to figure out when demand curves would start and end.
This made planning for the future incredibly difficult, which is why it didn't have the production capacity ready to go to meet the massive demand wave. This is in contrast to logic chip manufacturers like Taiwan Semiconductor (NYSE: TSM), which have contractual agreements that help them understand future demand.
However, Micron is now shifting its business toward that. It has signed several multi-year agreements through 2030 that set floor and ceiling prices on memory chips, and has now locked in about 35% of revenue through 2030. This is a huge deal for Micron, as it will smooth out its business and reduce investors' concerns about cyclical downturns when demand is lower. While Micron may not have the same strong results it's producing today, the floor will be much higher, leading to a more stable business that mirrors its logic-chip peers, like TSMC.
Currently, TSMC trades at 24 times forward earnings, while Micron stock changes hands at just 5.1 times forward earnings.
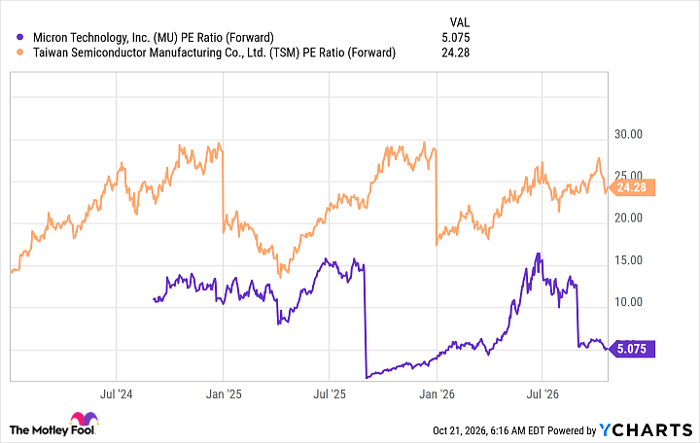
MU PE Ratio (Forward) data by YCharts. PE = price-to-earnings.
Should the market realize that Micron's business is transforming into a more sustainable one, Micron's stock could undergo a dramatic repricing, delivering incredible returns in a very short time frame. That would make Micron a perfect stock to scoop up now, and I think prudent investors should take advantage of that while it's beaten down.
Eventually, the market will realize that Micron is a solid long-term investment due to this business model shift, and that it deserves a more average multiple, rather than a huge discount.
Should you buy stock in Micron Technology right now?
Before you buy stock in Micron Technology, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Micron Technology wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $355,124!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,296,254!*
Now, it’s worth noting Stock Advisor’s total average return is 901% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 25, 2026.
Keithen Drury has positions in Micron Technology and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Micron Technology and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


