


Here's Why AMD Investors Should Consider Selling Before Nov. 3
Key Points
AMD's valuation has gotten out of control.
AMD is still underperforming Nvidia's business results, and trades at a substantial premium to it.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
AMD (NASDAQ: AMD) has been a tremendous stock to own in 2026. It has risen about 150% this year, ranking in the top 10 for best-performing S&P 500 (SNPINDEX: ^GSPC) stocks. That's an admirable performance, and it has AMD investors believing that it's truly taking ground from primary competitor Nvidia (NASDAQ: NVDA) in the all-important data center market.
However, I think some of this performance isn't earned, and the stock could be ripe for a pullback. There are several factors that point to this potentially coming, and getting out of the stock before AMD's Nov. 3 earnings report could save investors from some heartache.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: The Motley Fool.
AMD's stock is very expensive
At face value, AMD's stock is not cheap, regardless of which valuation measure you use.
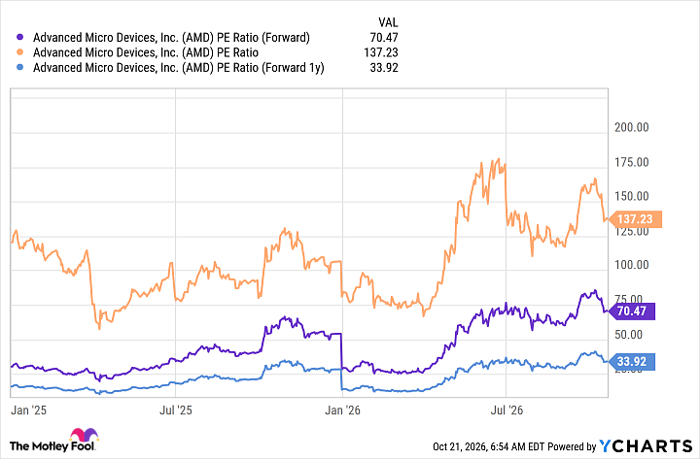
AMD PE Ratio (Forward) data by YCharts. PE = price-to-earnings.
At nearly 140 times trailing earnings, it's very pricey for the results it has delivered. Even at 70 times this year's earnings, it's still expensive. Analysts expect a huge year next year, with it trading at 34 times next year's earnings, but that's still just a very expensive stock, especially when compared to Nvidia.
Nvidia is AMD's nemesis in the data center space, and these two have competed against each other for a long time. Nvidia has nearly always been the winner, but from an investment standpoint, that has shifted in 2026. However, I don't think that has really been earned.
AMD's price tag has increased dramatically throughout the year, as evidenced by the chart above. While AMD trades for 34 times next year's earnings, Nvidia trades for 27 times trailing earnings. That's right, Nvidia is cheaper right now than AMD is projected to be at the end of next year if its stock price stays flat.
That's a huge pricing mismatch for companies in the same industry, and I think all of that could come to a head during AMD's third-quarter results.
AMD needs to continue accelerating its growth to justify its price
During AMD's second-quarter results, it reported accelerating data center revenue, rising 107% year over year to $6.7 billion. However, overall company revenue accelerated at just a 50% pace to $11.5 billion. That's because AMD's non-data center business units didn't have great quarters, and they are a drag on AMD's overall financial picture.
Contrast that with Nvidia, which delivered 117% data center growth to $89 billion and overall growth of 106% to $96.2 billion in Q2, and it's pretty clear that AMD is still behind Nvidia. There's nothing in those figures that points to AMD being worth a massive premium over Nvidia, and as soon as the market realizes it, one of two things will happen.
First, AMD stock could come under heavy selling pressure. As many funds look to take gains from 2026 returns and roll them into new 2027 ideas, AMD could be the first one on the chopping block due to it being a bit pricey. This could ignite a sell-off that returns AMD's valuation to a far more reasonable level. Depending on what is said in its Nov. 3 earnings report, this event could be the kick-start, unless it reports a major increase in data center revenue growth.
Second, Nvidia's stock could rotate back to being the darling of the stock market and see its price rise to a more reasonable valuation level. Regardless, I think it's pretty clear that AMD could have a period of underperformance arriving while Nvidia outperforms.
Taking advantage of AMD's high price tag and Nvidia's low price tag makes a lot of investment sense. Investors should consider rotating out of AMD and into Nvidia, as all indicators point toward that being a major trend during 2027.
Should you buy stock in Advanced Micro Devices right now?
Before you buy stock in Advanced Micro Devices, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Advanced Micro Devices wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $361,596!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,303,935!*
Now, it’s worth noting Stock Advisor’s total average return is 910% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 24, 2026.
Keithen Drury has positions in Nvidia. The Motley Fool has positions in and recommends Advanced Micro Devices and Nvidia. The Motley Fool has a disclosure policy.
Recommended Articles


