


Western Digital Stock Price Forecast: Tumbles Over 3% Ahead of Earnings, Could Fall Another 18%
TradingKey - Western Digital slips over 3% ahead of earnings, faces potential 18% plunge to $300 mark if results disappoint.
On October 22 Eastern Time, Western Digital (WDC)'s stock rebound stalled, falling 3.4% in pre-market trading to $365.71. On Monday (October 19), Western Digital's stock fell to $330, touching its April low for the year while expanding its year-to-date maximum drawdown to 58%.
WDC's sharp drop ahead of earnings was mainly driven by slowing demand for PCs and smartphones. Although demand for cloud and enterprise nearline hard drives remains strong, consumer PC and NAND Flash prices showed weakness in Q4, triggering a de-rating by quantitative funds on the gross margins of its legacy Flash business.
In addition, against the backdrop of a market-wide deleveraging shakeout in high-valuation semiconductor and data storage sectors, coupled with surging U.S. Treasury yields pressuring tech stock valuations, memory and storage giants such as Micron Technology (MU), SK Hynix (SKHY), and SanDisk (SNDK) all faced selling pressure, and Western Digital was no exception.
Currently, the market expects Western Digital's Q1 FY2027 revenue to reach $4.15 billion, with earnings per share (EPS) surging 130.3% year-over-year to $4.10. If EPS and revenue top expectations and management provides strong preliminary guidance for Q2 and the full year, the stock is expected to immediately reclaim the $400 mark on heavy volume and return to its primary bullish upward trend.
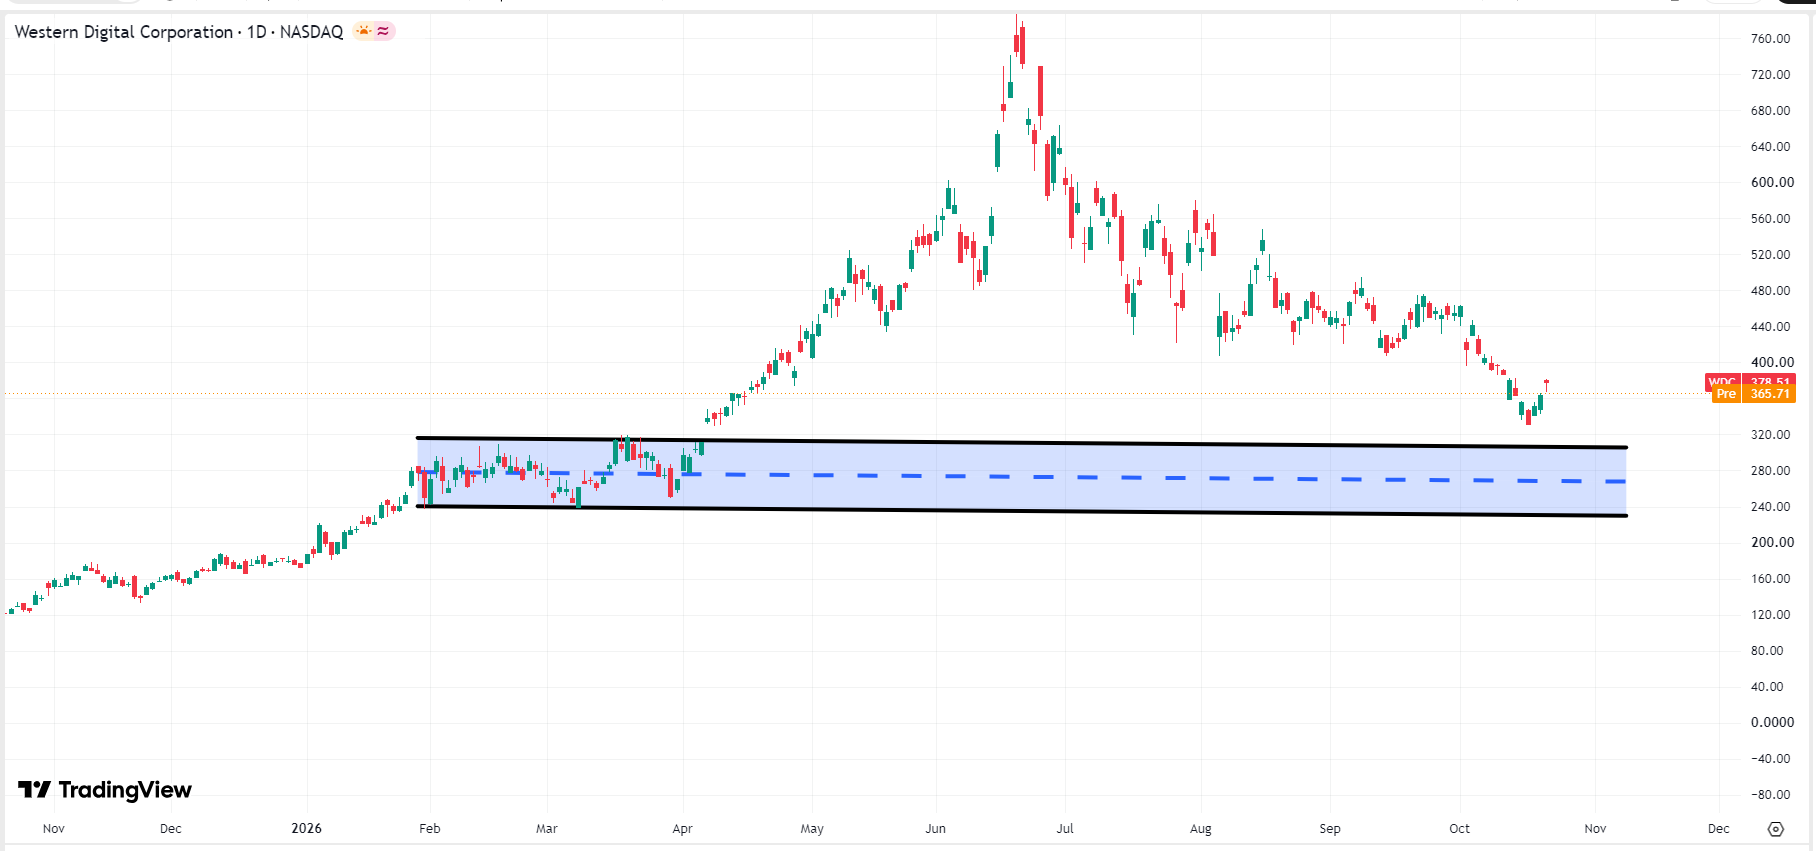 Western Digital stock price chart, Source: TradingView
However, if Western Digital's Q1 post-market earnings guidance falls short of expectations, the stock could plummet another 18% toward the $300 mark, where the 200-day moving average converges with the major trading volume center from the first half of the year. Before retreating to $300, strong institutional buying support has accumulated around $330, where bulls are expected to counterattack, creating potential for a minor rebound.
Recommended Articles


