


Prediction: Taiwan Semiconductor Manufacturing Stock Will Skyrocket After Oct. 15
Key Points
A price hike announcement from Taiwan Semiconductor could send shares soaring.
Projections from some of its clients indicate huge growth ahead.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Taiwan Semiconductor Manufacturing (NYSE: TSM) has a major event coming up in a few weeks: third-quarter earnings. This could have huge implications not only for Taiwan Semiconductor's stock, but also for everyone else involved in the AI arms race, because it's such a key supplier in the industry.
I think it will have positive news to report, but there are a few things that I'm looking for to confirm the bull case. If everything goes well, I could see the stock taking off, as it's projected to grow at the fastest rate it has ever grown during the AI arms race.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Taiwan Semiconductor Manufacturing Company.
Taiwan Semiconductor is one of the best AI investments out there
Although it's not talked about as much as some of the other major AI companies out there, Taiwan Semiconductor is a leading AI investment pick. The reason is pretty clear: It provides a huge chunk of chips for the industry. During Q2, Taiwan Semiconductor accounted for an estimated 72.5% of the world's chip foundry revenue. That shows just how much of a lead it has over its peers, and that size advantage is a nearly unbreakable moat.
The reality is, even if TSMC's clients were disgruntled and wanted to leave, they couldn't. Nobody else has the production capacity available to match it. However, none of TSMC's clients are upset, as its technology and execution make it an excellent company to work with.
So, as long as there is more spending on AI chips, TSMC should continue to be a viable investment. Fortunately for investors, that's where the market is heading. One of TSMC's largest clients, Nvidia (NASDAQ: NVDA), expects the big five AI hyperscalers to spend nearly $800 billion in data center capital expenditures this year. Next year, that figure rises to $1.3 trillion. Ultimately, they see global data center capital expenditure costs rising to $3 trillion to $4 trillion annually by 2030. That means the market for chips is rising, and with nearly three-fourths of the world's chips (at least by revenue) coming from TSMC, there's a huge growth runway ahead for it.
And that's starting to show up in TSMC's results.
The market expects a strong quarter from TSMC
Wall Street analysts expect an average of 47% revenue growth this quarter and 53% in the next. Those are monster growth figures, and each is far higher than anything Taiwan Semiconductor has produced over the past few quarters.
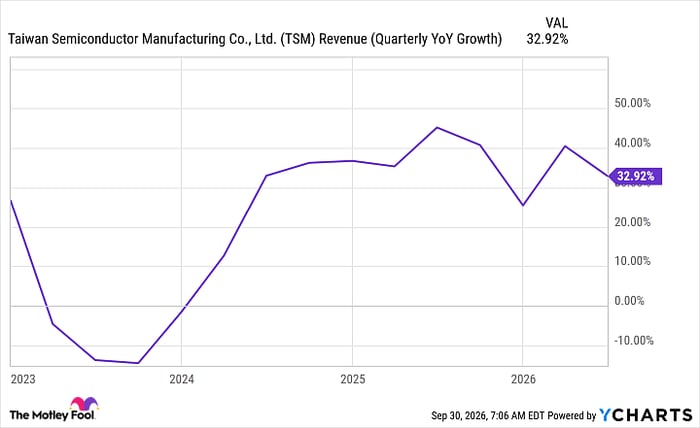
TSM Revenue (Quarterly YoY Growth) data by YCharts
These elevated growth rates indicate that TSMC is seeing an increase in volume, but it also could be because it's raising its prices. Taiwan Semiconductor is in an excellent position to raise prices, and language from some of the major computing chip suppliers suggests that some of their chip costs are already rising, so they are raising their prices as a result.
I'll be looking to see if TSMC says it's raising prices, as that will point toward strong results lasting into 2027, which could pose significant upside for the stock.
Right now, Taiwan Semiconductor actually trades at a pretty reasonable valuation of 27 times forward earnings.
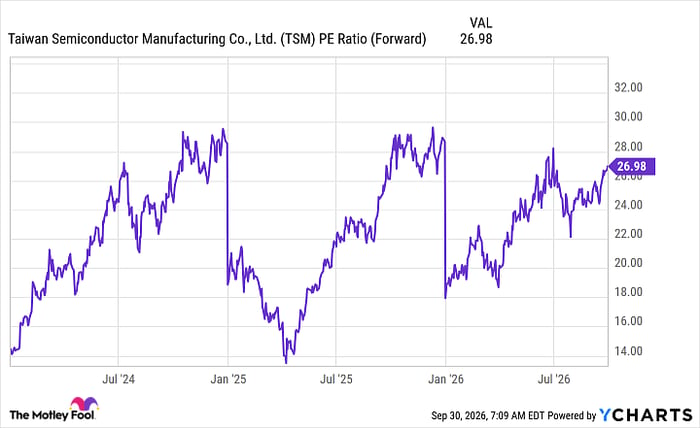
TSM PE Ratio (Forward) data by YCharts
That's on the higher end of where it has traded over the past two years. Still, if its growth is faster than anything it has previously experienced, then a higher valuation is probably warranted. Regardless, TSMC looks like it's set up to have another strong year in 2027, so I think the stock will likewise continue its success over the next few years.
Taiwan Semiconductor is in a great spot as a business, and if it says the right things, I won't be surprised to see the stock move far higher following its earnings release on Oct. 15.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $375,240!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,403,292!*
Now, it’s worth noting Stock Advisor’s total average return is 932% — a market-crushing outperformance compared to 211% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 1, 2026.
Keithen Drury has positions in Nvidia and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Nvidia and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


