


History Says Johnson & Johnson Beats Medtronic. Here's Why I'd Still Consider MDT for the Next Decade.
Key Points
Johnson & Johnson has significantly outperformed Medtronic over the past decade.
Much of its outperformance started with its 2021 decision to spin off its consumer healthcare business.
Medtronic is following that same strategy by spinning off its diabetes business.
- 10 stocks we like better than Johnson & Johnson ›
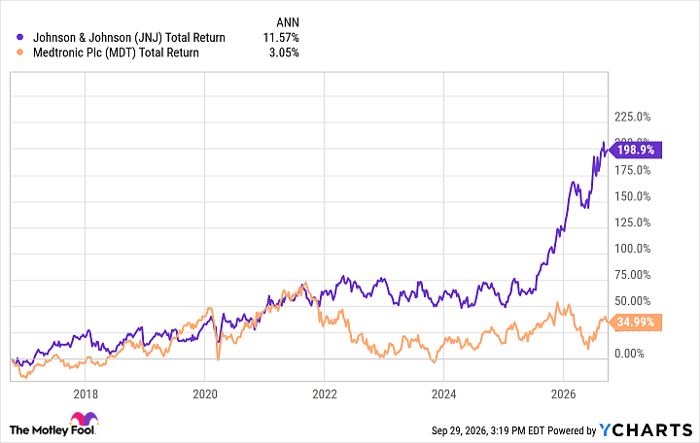
Johnson & Johnson's (NYSE:JNJ) stock has absolutely crushed Medtronic's (NYSE:MDT) over the last decade. The iconic healthcare giant has generated a nearly 200% total return over the last 10 years (11.6% annualized), compared with roughly 35% for the healthcare technology company (3.1% annualized).
However, while Johnson & Johnson's stock was the clear winner over the past decade, I think Medtronic could be the better investment over the next 10 years. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »

Image source: Getty Images.
The breakout decision
Shares of Johnson & Johnson and Medtronic ran neck-and-neck for the first half of the past decade. However, the global healthcare behemoth started separating itself from its smaller rival in late 2021 before really taking off over the past year:
JNJ Total Return Level data by YCharts
The initial catalyst coincides with the company's decision in late 2021 to spin off its consumer healthcare business (now Kenvue). The move has paid major dividends for shareholders by unlocking the value of its businesses. It also provided JNJ with additional capital to reinvest in the growth of its innovative medicines and MedTech divisions.
The company has made several acquisitions to expand both segments over the past few years. Notable deals include Abiomed ($16.6 billion in 2022), Shockwave Medical ($13.1 billion in 2024), and Intra-Cellular Therapeutics ($14.6 billion in 2025). These deals accelerated growth for its MedTech segment and strengthened its leadership in neuroscience and other crucial areas.
Johnson & Johnson is currently evaluating its next opportunity to unlock shareholder value. It's considering a spin-off or sale of its orthopedics unit (DePuy Synthes) and is reportedly close to a $20 billion deal to sell it to a private equity firm. A sale would give Johnson & Johnson even more capital to put to work in enhancing the growth of its remaining businesses.
Repeating a winning play
Much of Johnson & Johnson's outperformance over the latter part of this past decade stems from its decision to spin off Kenvue. That's likely one of the factors driving Medtronic's current strategy. Last year, the company announced plans to separate its diabetes business (MiniMed) to unlock shareholder value. It's following the exact winning playbook of Johnson & Johnson as it initially completed an IPO of the unit and recently launched an exchange offer to finish the separation, which it should complete later this month.
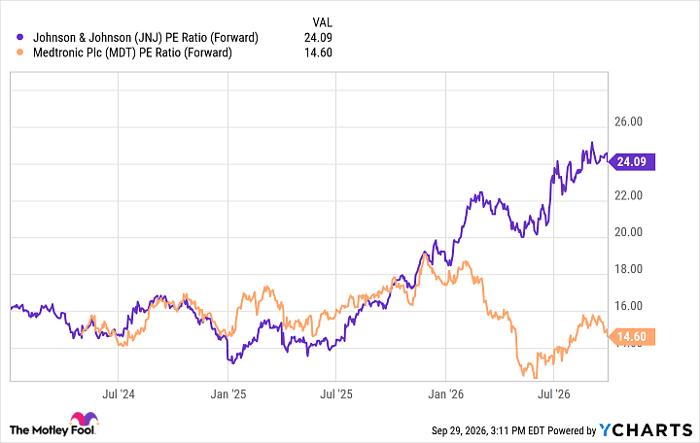
The hope is that this move will be the catalyst to start unlocking the value of its stock, which now trades at a wide discount to Johnson & Johnson:
JNJ PE Ratio (Forward) data by YCharts
That lower starting valuation is one reason why I think Medtronic could beat JNJ stock over the next decade. It's also why the medical technology company currently has a much higher dividend yield than its larger rival (3.3% vs. 2%).
The separation of MiniMed will enable Medtronic to focus on its highest-margin growth drivers (cardiovascular, neuroscience, and medical-surgical). They're all large and growing markets (mid-to-high single digits). That positions the company to deliver a similar growth rate as it takes market share by launching new products and continuing to make acquisitions to enhance its product portfolio. It has purchased SPR Therapeutics, CathWorks, and Scientia Vascular for nearly $1.8 billion combined this year.
The company's growing earnings should enable it to continue increasing its dividend. Medtronic extended its streak to 49 consecutive years in 2026. While that's well behind Johnson & Johnson's 64-year dividend growth streak, it has Medtronic on the cusp of joining its healthcare rival as a Dividend King (a company with 50 or more years of annual dividend increases).
Medtronic's next decade should be better than the last one
Johnson & Johnson's spinoff strategy proved to be a meaningful catalyst for its stock over the past 10 years, enabling it to deliver much higher returns than Medtronic. I think this history foreshadows a better future decade for Medtronic because it's following the same winning playbook. Its current combination of a lower relative valuation and a higher dividend yield should enable it to deliver a higher total return over the next 10 years, as long as its strategy accelerates growth as it did for JNJ.
Should you buy stock in Johnson & Johnson right now?
Before you buy stock in Johnson & Johnson, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Johnson & Johnson wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $379,123!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,396,103!*
Now, it’s worth noting Stock Advisor’s total average return is 933% — a market-crushing outperformance compared to 212% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 1, 2026.
Matt DiLallo has positions in Johnson & Johnson and Medtronic. The Motley Fool has positions in and recommends Medtronic. The Motley Fool recommends Johnson & Johnson and Kenvue. The Motley Fool has a disclosure policy.
Recommended Articles


