


Prediction: Here's What a $5,000 Investment in Qualcomm Could Be Worth by 2030
Key Points
Qualcomm has underperformed the broader semiconductor sector over the past five years, but its fortunes could change.
The company's entry into the AI chip market and the growth of the non-handset business will be tailwinds for the stock.
Now seems like a good time for savvy investors to get into Qualcomm before it surges higher.
- 10 stocks we like better than Qualcomm ›
The past five years have been painful for Qualcomm (NASDAQ: QCOM) investors. The company's dependence on the smartphone market for a significant chunk of revenue has weighed on the stock during this period.
Qualcomm stock has appreciated just 47% over the past five years, underperforming the broader semiconductor sector. The PHLX Semiconductor Sector shot up by 272% during the same period, driven by the incredible demand for artificial intelligence (AI) chips.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
However, Qualcomm has now jumped onto the AI bandwagon. I won't be surprised to see this semiconductor stock step on the gas over the next five years, driven by its entry into the AI chip market. Let's look at the potential upside Qualcomm could deliver by the end of the decade.
Image source: The Motley Fool.
Qualcomm could clock stronger growth due to AI
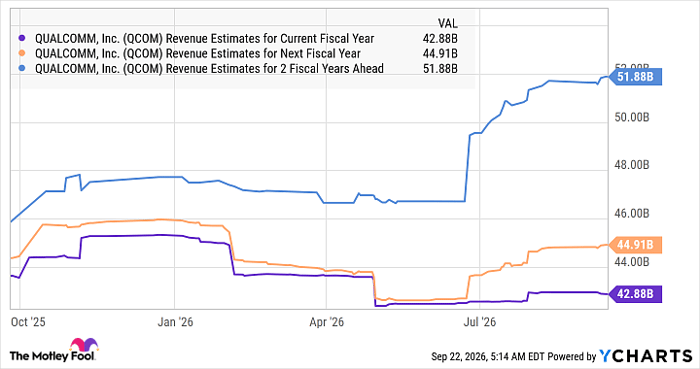
Qualcomm's revenue in the first nine months of the ongoing fiscal 2026 dropped on a year-over-year basis to $32.8 billion from $33 billion in the same period last year. Analysts are anticipating that the company's revenue will contract nearly 3% this fiscal year to $42.9 billion. The poor top-line performance will negatively impact Qualcomm's bottom line, with its earnings per share projected to drop by 13% in fiscal 2026.
Counterpoint Research predicts a 14% drop in smartphone shipments this year. Qualcomm gets 51% of its revenue from the smartphone segment, which explains why the industry's poor performance is poised to weigh on its financial performance. The smartphone market's decline is anticipated to slow down to 1% next year, followed by a 5% increase in shipments in 2028.
So, Qualcomm's largest business could step on the gas by the end of the decade. Additionally, Qualcomm's entry into AI chips and its fast-growing automotive business are poised to drive stronger growth. The company expects its non-handset revenue to hit $40 billion in fiscal 2029. Qualcomm notes that $24 billion of this revenue will come from the automotive and Internet of Things (IoT) businesses, while the remaining will come from the data center segment.
Importantly, Qualcomm has nearly doubled its non-handset revenue forecast for 2029 from the original estimate of $22 billion. This can be attributed to the growth in the data center segment. Qualcomm sees the data center business clocking $5 billion in revenue in fiscal 2027 and $15 billion in fiscal 2029. This impressive acceleration will be driven by the growing adoption of Qualcomm's chips by major hyperscalers, such as Amazon.
Here's how much upside the stock can deliver by 2030
Qualcomm's fiscal 2026 will end this month. We have already seen that its top line will contract this fiscal year. The good news for investors is that the company is poised to return to growth from fiscal 2027, followed by a strong acceleration in revenue in fiscal 2028.
Data by YCharts
Qualcomm can sustain such solid growth in fiscal years 2029 and 2030 as well due to the reasons discussed above. Assuming its top line increases by 15% in each of those two fiscal years, it could reach $68.6 billion by the end of the decade.
Qualcomm trades at 4.3 times sales right now, a discount to the Nasdaq Composite index's sales multiple of 5.2. An acceleration in the company's top-line growth should ideally be rewarded with a premium multiple.
Assuming Qualcomm trades at 6 times sales at the end of fiscal 2030 and its revenue jumps to $68.6 billion, its market cap will increase to $412 billion. That's nearly double its current market cap, which means an investment of $5,000 in this stock could be worth over $10,000 in 2030.
Should you buy stock in Qualcomm right now?
Before you buy stock in Qualcomm, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Qualcomm wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $389,154!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,406,303!*
Now, it’s worth noting Stock Advisor’s total average return is 949% — a market-crushing outperformance compared to 214% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 23, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Amazon and Qualcomm. The Motley Fool has a disclosure policy.
Recommended Articles


