


Prediction: Networking Will Be the Next Bottleneck Within the AI Supercycle. 1 Growth Stock to Own.
Key Points
Fast networking components play a critical role in AI data centers to ensure that AI accelerator chips can be fed with large data sets quickly.
Arista Networks' improving revenue pipeline suggests that its healthy growth momentum is sustainable.
Arista can outperform Wall Street's expectations and deliver more upside following a nice jump in its stock price this year.
- 10 stocks we like better than Arista Networks ›
The artificial intelligence (AI) infrastructure supercycle has created tremendous demand for many hardware components, including accelerator chips and memory.
A supercycle refers to a period of strong demand for products or services that exceeds supply. Not surprisingly, the AI supercycle has created a shortage of memory chips, graphics cards, and server processors. And now, a new bottleneck is emerging thanks to the AI infrastructure supercycle in the networking market.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
AI data centers need fast networking to exchange large data sets quickly and ensure that accelerators don't sit idle and waste energy. As a result, the demand for networking components, such as routers and switches, is increasing at a fast clip and overwhelming supply. Goldman Sachs expects optical networking revenue to jump by more than 10x between 2026 and 2028, creating a supply shortage.
Arista Networks (NYSE: ANET) has emerged as a major beneficiary of this boom, with its shares rising more than 57% in 2026. Let's look at the reasons why this growth stock has the potential to deliver more gains.
Image source: Getty Images.
Arista Networks is growing at a solid clip thanks to the AI networking boom
Arista Networks sells networking hardware and software, including Ethernet switches and routers. The company is capitalizing on the AI networking boom by designing high-performance network architecture to connect AI training and inference clusters. The demand for Arista's AI networking fabric is increasing at a solid clip.
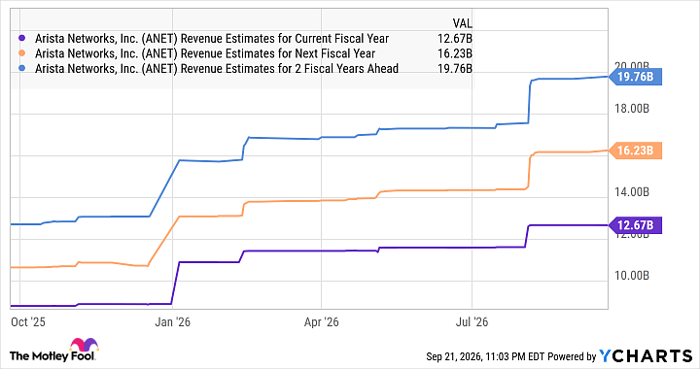
Management noted on the August earnings call that it now has more than 100 customers using its Etherlink AI networking fabric, up from just 4-5 customers in 2024. Arista expects to generate at least $3.5 billion from customers deploying its AI networking fabrics this year, or around 27% of the $12.7 billion revenue it is anticipated to clock in 2026, according to consensus estimates.
Importantly, Arista's revenue pipeline is improving at an incredible clip. The company's purchase commitments rose to $9.7 billion in Q2, significantly higher than the $3.6 billion figure in the year-ago period. Management attributed this impressive spike to "purchases for chips related to new products and AI deployments."
The improving revenue pipeline explains why Arista's growth trajectory is improving. The company reported a 38% year-over-year increase in revenue in Q2 to $3.04 billion, an improvement over the 35% jump it reported in Q1. More importantly, Arista's revenue estimate of $3.3 billion points to a potential year-over-year increase of 43%.
What's worth noting is that Arista is growing almost in line with the global Ethernet switch market. Market research firm IDC estimates that sales of Ethernet switches increased 43% in the second quarter to $18.9 billion. The acceleration in Arista's growth rate indicates it is on track to capture a larger share of this opportunity.
So, it is easy to see why analysts have increased their revenue expectations following the company's latest quarterly report.
Data by YCharts
Is this growth stock still a good buy?
The healthy jump in Arista stock this year explains why it trades at an expensive 63 times trailing earnings. However, the forward earnings multiple of 38 is significantly cheaper, suggesting a big jump in its bottom line.
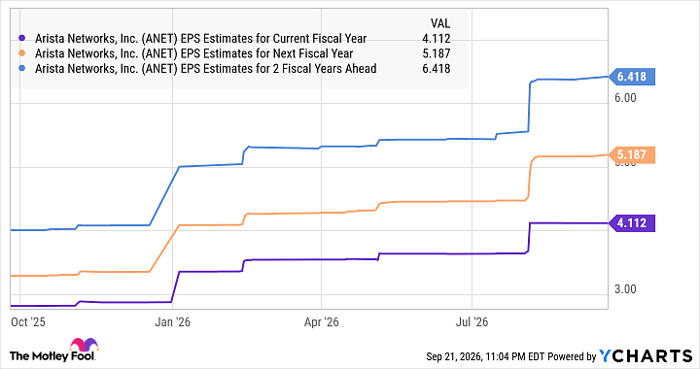
What's more, the company's robust revenue growth will positively impact its bottom line, which explains why analysts have significantly raised their long-term earnings growth expectations.
Data by YCharts
I won't be surprised to see Arista clocking stronger earnings growth over the long run, paving the way for more upside. So, investors looking to buy an AI stock to capitalize on booming networking demand would do well to take a closer look at Arista before it flies higher.
Should you buy stock in Arista Networks right now?
Before you buy stock in Arista Networks, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Arista Networks wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $395,625!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,397,147!*
Now, it’s worth noting Stock Advisor’s total average return is 951% — a market-crushing outperformance compared to 214% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 22, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Arista Networks and Goldman Sachs Group. The Motley Fool has a disclosure policy.
Recommended Articles


