


Prediction: $5,000 Invested in Taiwan Semiconductor Could Be Worth This Much by 2030
Key Points
Taiwan Semiconductor Manufacturing (TSMC) has a virtual monopoly on manufacturing advanced AI chips.
TSMC has leaned on its pricing power to increase profits and expand its margins.
Momentum from the current AI infrastructure build-out should continue through the next few years.
- 10 stocks we like better than Taiwan Semiconductor Manufacturing ›
Taiwan Semiconductor Manufacturing (NYSE: TSM) has been one of the best-performing big tech stocks over the past three years, up 380%. That's better than every "Magnificent Seven" stock in that time, and it hasn't shown many signs of slowing down. As of this writing, it's up over 45% for the year.
Although it's not often considered a typical AI stock, TSMC's latest run is largely driven by the ongoing AI boom. As the world's largest semiconductor (chip) foundry, TSMC is as valuable to the AI ecosystem as virtually any company in the mix. And that's why I'm confident a $5,000 investment in the stock could grow to $8,000 by 2030. Let's take a deeper dive.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
So, what exactly does TSMC do?
TSMC is the go-to chip manufacturing company for many of the electronics we use daily. While companies like Apple design their iPhone chips, Nvidia designs chips for its data center hardware, and Broadcom designs chips for its networking equipment, they all rely on TSMC to actually manufacture them.
No company has TSMC's expertise, results, and scale, so it's in a league of its own. It has a 73% market share in the foundry market, but its share of advanced AI chips is well into the upper 90% range. It has been using that to its advantage, too.
The data centers that AI hyperscalers like Amazon, Microsoft, Alphabet, and Meta Platforms are spending trillions to build are filled with advanced chips made by TSMC. So, no matter which of those companies pulls ahead in the AI race, TSMC will continue to benefit. That's a lucrative position to be in.
Profits continue to flow
TSMC's virtual monopoly has given it lots of pricing power. Companies either pay a premium for chips they know will be high-performance and meet the required scale, or go with a less efficient alternative and risk performance. TSMC's market shows which option companies generally choose.
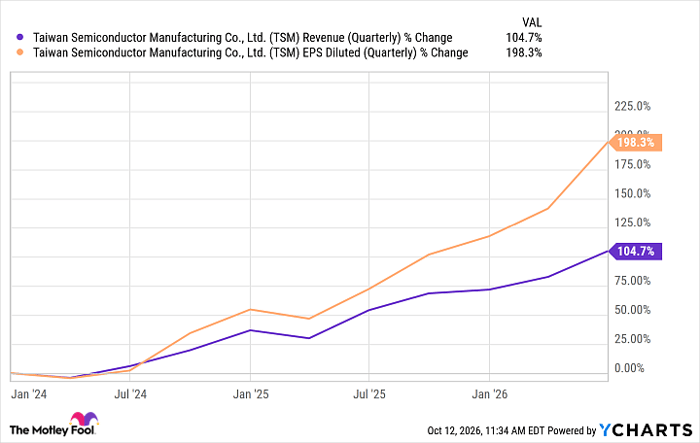
Its revenue growth over the past few years has been impressive (up 33.7% year over year in the second quarter), but earnings growth has been even more explosive.
TSM Revenue (Quarterly) data by YCharts
Over the same three-year span, its gross margin rose from 54.1% to 67.7%, operating margin from 42% to 60.3%, and net profit margin from 37.8% to 55.6%.
How much a $5,000 investment could be worth by 2030
For illustration, let's assume TSMC's stock price remains flat through the rest of 2026. That means the stock would need to grow 60% from 2027 to 2030, averaging 17% returns per year. Right now, TSMC is a $2.3 trillion company trading at 26.5 times its projected 2027 earnings, which is on the high end of its average over the past three years.
If we assume this holds steady over three years, TSMC would need to grow its earnings per share (EPS) by around 15.6% annually. That's more than feasible for a company that has grown by 198% over the past three years. Current estimates put TSMC's year-over-year EPS growth well above that for the next couple of years, but even if it cuts back modestly to 20% after, a $5,000 investment can easily grow to $8,000. And 20% is on the low end of what I expect the growth to be.
AI is fueling TSMC's current momentum, but its business goes beyond that. Even if AI momentum slows over the next three or so years, TSMC's business is broad and deep enough to keep thriving. Margins would likely take a hit, but I don't imagine the company or investors would harp on it too much.
We can't predict how stock prices will move -- and good business or financial performance doesn't guarantee good stock price performance -- but I think TSMC's stock still has enough momentum to turn $5,000 into $8,000 by 2030.
Should you buy stock in Taiwan Semiconductor Manufacturing right now?
Before you buy stock in Taiwan Semiconductor Manufacturing, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Taiwan Semiconductor Manufacturing wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $380,795!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,390,634!*
Now, it’s worth noting Stock Advisor’s total average return is 946% — a market-crushing outperformance compared to 215% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of October 14, 2026.
Stefon Walters has positions in Apple, Microsoft, and Taiwan Semiconductor Manufacturing. The Motley Fool has positions in and recommends Alphabet, Amazon, Apple, Broadcom, Meta Platforms, Microsoft, Nvidia, and Taiwan Semiconductor Manufacturing. The Motley Fool has a disclosure policy.
Recommended Articles


