


EUR/USD Weekly Forecast: Surprise, Surprise! NFP Pushes Fed Towards Rate Cut
The EUR/USD pair bottomed at 1.1391 on the first day of August, its lowest in over a month. The US Dollar (USD) found legs regardless of the market sentiment, maintaining its positive momentum throughout quite a busy week.
However, USD finally gave up on Friday after dismal United States (US) data. The pair finally settled at around 1.1550, still holding onto substantial weekly losses.
Trade War Back and Forth
The US and the European Union (EU) reached a trade deal that sets a 15% tariff for most US exports and calls for EU investments in various American sectors. A 50% levy for EU exports to the US will remain in place on steel, aluminium and copper.
Meanwhile, additional details are still missing. European Commission President Ursula von der Leyen noted such levies are subject to reciprocal tariffs. But he didn’t provide much detail on whether or when the EU would announce them.
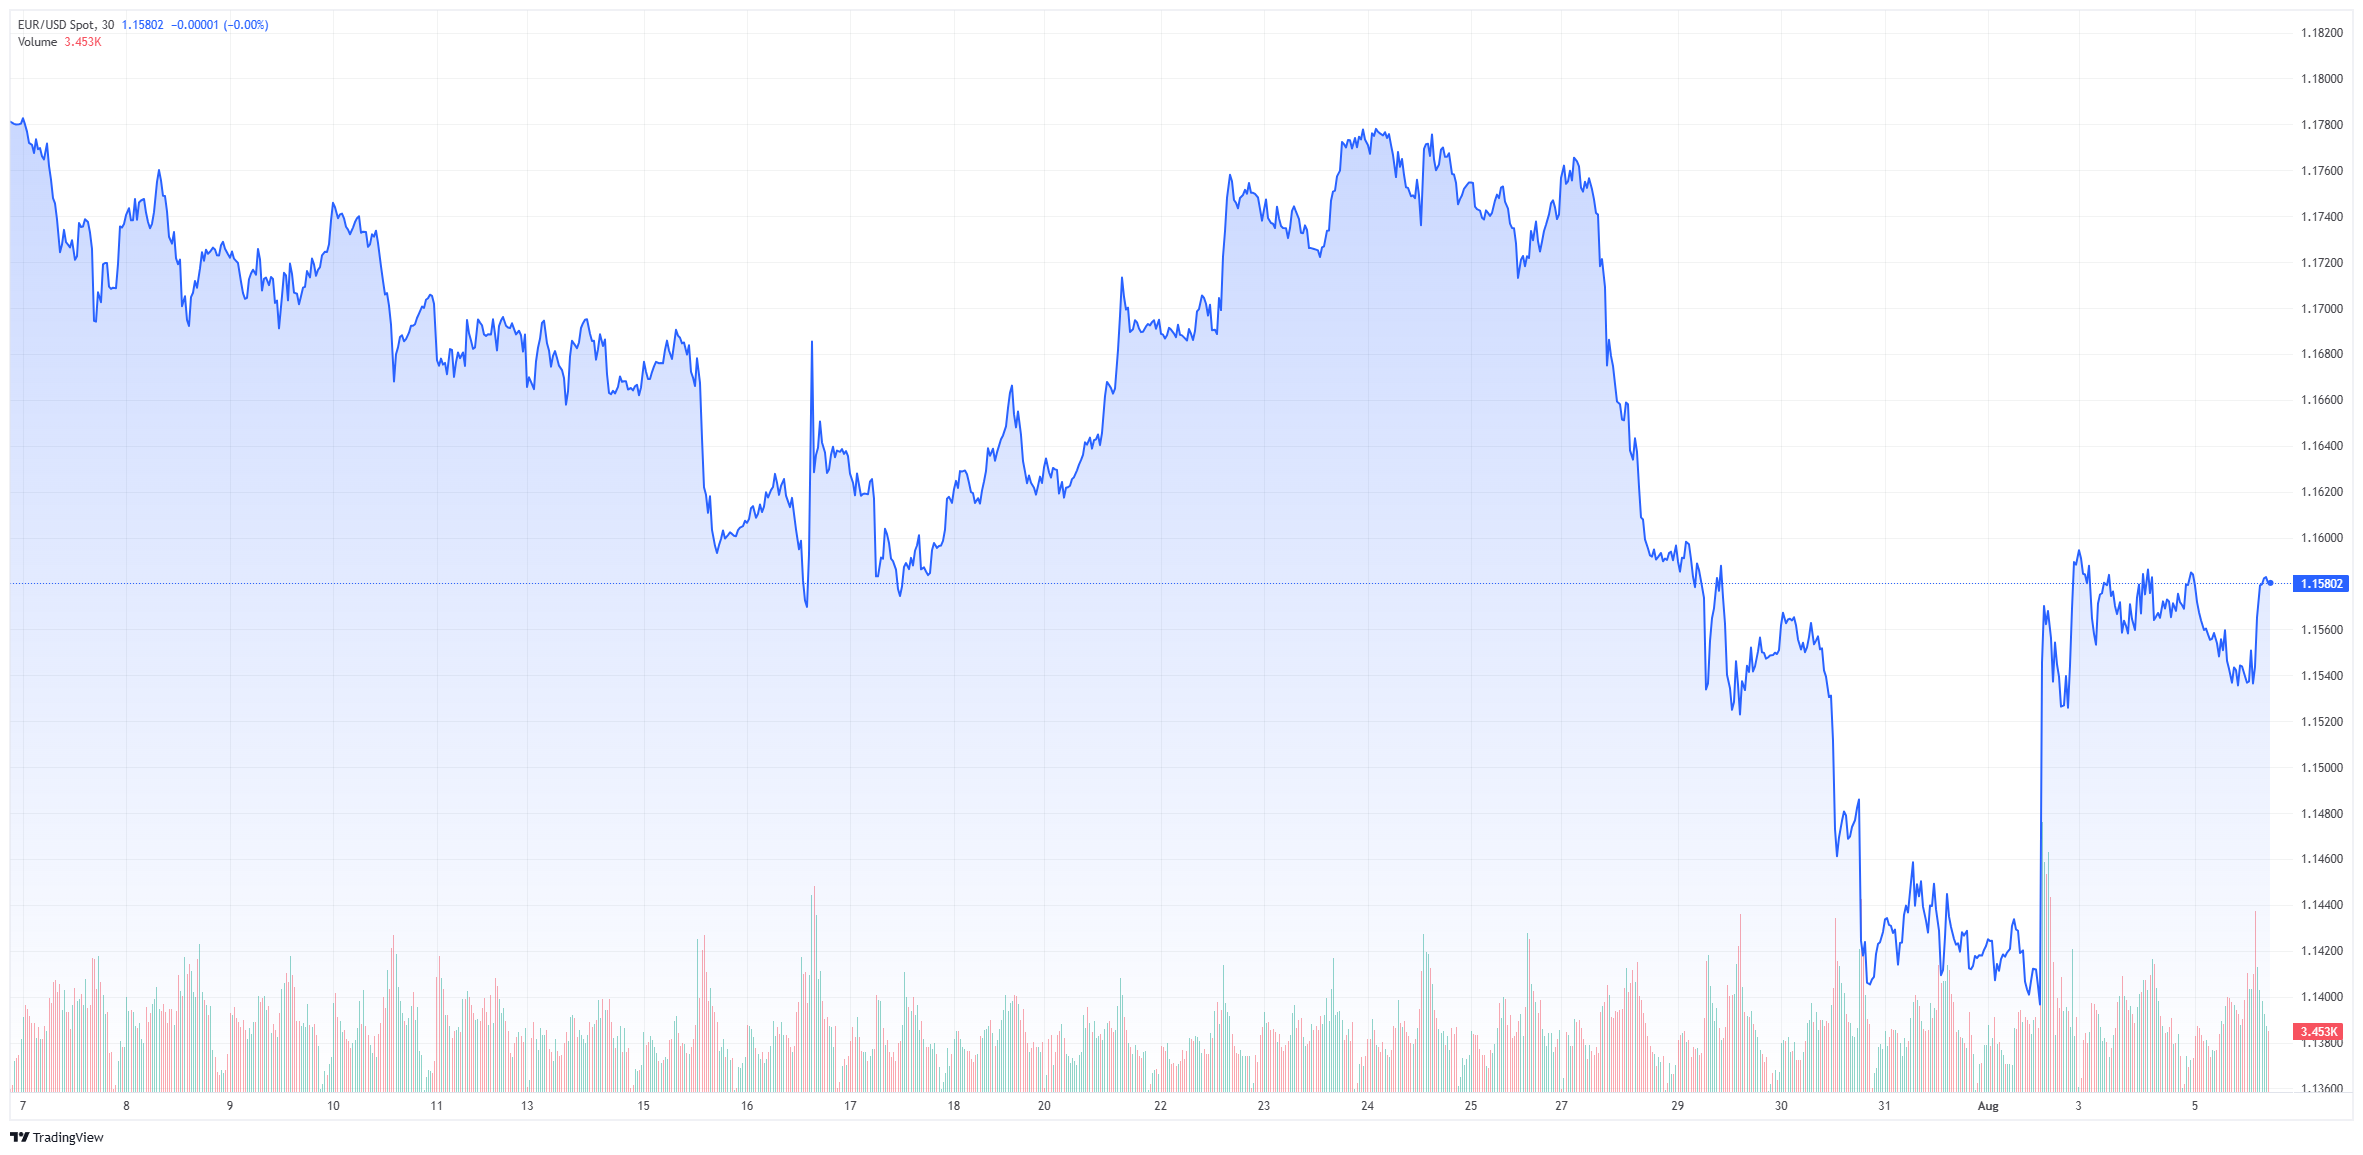 EUR/USD Monthly Chart. Source: FXStreet
European leaders widely criticized the deal, with German Chancellor Friedrich saying it will cause “considerable damage” and French Prime Minister François Bayrou calling it “a dark day” for the EU.
Mid-week, US President Donald Trump announced a 50% levy on all Brazilian imports into the US. It was meant as a “punishment” to the lefty government.
The White House also announced a universal 50% tariff on imports of semi-finished copper products and copper-intensive derivative products.
Finally, the August 1 deadline took effect on Friday, spreading fresh tariffs. With neighbour Mexico, Trump agreed to a 90-day extension in levies for additional negotiations, but hit Canada with a 35% tariff.
Stock markets collapsed ahead of the weekly close. The decline reflected the market’s concerns about the potential effect of this decision on global economic progress.
Federal Reserve’s Rebellion
Also, mid-week, the Federal Reserve (Fed) announced its decision on monetary policy. As widely anticipated, policymakers left the benchmark interest rate unchanged, floating between 4.25% and 4.50%.
However, the decision included a surprise. For the first time in decades, two dissenters, Governors Christopher Waller and Michelle Bowman, voted to reduce borrowing costs.
Nevertheless, Chair Jerome Powell explained that such a decision resulted from the persistent uncertainty related to the tariffs’ impact on inflation.
Powell also explained that with inflation still above the Fed’s 2% goal and the labor market still tight, the central bank should keep rates at their current levels. According to Powell, this decision leaves policymakers well-positioned to respond in a timely way.
Powell did not hint at a potential interest rate cut when they met in September. He prefers to maintain his wait-and-see stance.
The decision triggered another tantrum from President Trump, who has long been demanding lower rates. He used social media to attack the Fed’s head, calling Powell “Too Late,” and claiming his decision costs billions of dollars.

Trump’s Blasts Powell on Social Media
Data-packed Week Ending With a Bang
European data released these days showed that the Old Continent is coming out of the woods, thanks to the European Central Bank’s (ECB ) massive interest rate reduction.
Germany released the preliminary estimate of the Q2 Gross Domestic Product (GDP). It showed the economy contracted by 0.1% in the three months to June after advancing 0.4% in the previous quarter.
The country also released the preliminary estimate of the July Harmonized Index of Consumer Prices (HICP), which rose at an annualized pace of 1.8%, easing from the 2% posted in June.
Retail Sales in the country were up 4.9%. This was almost double the previous 2.6% advance.
The EU flash Q2 GDP posted a 0.4% quarterly gain, better than the 0.2% expected, while the annual advance was 1.4%, beating estimates of 1.2%.
On a negative note, the HICP held at 2% YoY in July according to preliminary estimates, against an expected 1.9%. The core annual reading also remained unchanged at 2.3%.
The US calendar was packed with employment-related data, ahead of the almighty Nonfarm Payrolls report. But the country also released the flash estimate of the Q2 GDP, which showed the US economy grew at an annualized rate of 3%, much better than the 0.5% decline from the first quarter and better than the 2.4% expected.
The upbeat figure fueled demand for the USD, which a hawkish Fed later exacerbated.
Regarding employment figures, the June Job Openings and Labor Turnover Survey (JOLTS) indicated that the number of job openings on the last business day of June stood at 7.43 million, below the 7.77 million openings (revised from 7.76 million) recorded in May and came in below the market expectation of 7.55 million.
The ADP Employment Change report released on Wednesday was more encouraging. It showed that the private sector added 104,000 new job positions in July, while the June loss was revised to 23,000 from the previous estimate of -33,000.
Finally, the Challenger Job Cuts showed US-based companies announced 62,075 job cuts in July, compared with almost 25,900 a year earlier. The reading was well above the 47,999 announced in June, as is the second-highest for a July in the past decade.
Non-Farm Payrolls Shock The Markets
The NFP finally came out, and all hell broke loose. The country added a measly 73,000 new positions in July, while the June reading was downwardly revised to 14,000 after previously reporting 147,000.
In fact, revisions showed roughly 260,000 fewer job positions than previously estimated in the last few months.
Additionally, the Unemployment Rate rose to 4.2% from 4.1% in July, as expected, while the Labor Force Participation Rate ticked down to 62.2% from 62.3%.
Finally, annual wage inflation, as measured by the change in the Average Hourly Earnings, rose to 3.9% from 3.8%.
The news put the US Dollar in sell-off mode. Following the Fed’s monetary policy announcement, speculative interest ran to bet on an on-hold decision in September, with the odds for a no-change surging to roughly 60%.
However, the awful monthly employment report flipped the sentiment. Market players now believe there is more than a 66% chance of a rate cut at the upcoming Fed meeting.

It is worth adding that, before the weekly close, the US also published the July ISM Manufacturing Purchasing Managers Index (PMI) that unexpectedly contracted to 48 from the 49 posted in June, also missing expectations of 49.5.
The Michigan Consumer Sentiment Index, in the meantime, was downwardly revised to 61.7 in July. This was following a preliminary estimate of 61.8, which was below the 62.0 anticipated.
By the end of the week, stocks retain substantial tariff-inspired losses, reflecting tariff-related concerns. Regardless of the loosening labor market, the risk of higher inflation remains the same.
With that in mind, the Fed may hold back its fire again in September.
In the upcoming days, the macroeconomic calendar will have little to offer. The most relevant figures will be the US July ISM Services PMI and the EU June Retail Sales. That said, the trade war will likely retake centre stage.
Read more
* The content presented above, whether from a third party or not, is considered as general advice only. This article should not be construed as containing investment advice, investment recommendations, an offer of or solicitation for any transactions in financial instruments.


