




Prediction: This AI Infrastructure Stock Will Go Parabolic After Sept. 30 (Hint: It’s Not Micron)
Key Points
Jabil will release its quarterly results on Sept. 30.
The company's financial performance has been improving amid the AI infrastructure boom.
Jabil stock could surge impressively over the next couple of years due to its strong earnings power and attractive valuation.
- 10 stocks we like better than Jabil ›
Micron Technology is a key player in the global artificial intelligence (AI) infrastructure ecosystem, which explains why the market will be eagerly awaiting the company's fiscal 2026 fourth-quarter results on Sept. 30.
Micron's results and guidance will give investors insight into the state of the AI infrastructure build-out. After all, the company's memory chips play a critical role in AI by transporting massive amounts of data rapidly in data centers and chip clusters. It won't be surprising to see Micron stock take off following its upcoming report, especially given the incredible demand for memory chips and tight supply.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there is another AI infrastructure stock poised to report results this month. Jabil (NYSE:JBL) is a manufacturing services provider that designs, engineers, and builds products for its customers. It serves multiple industries, such as healthcare, automotive, aerospace, and data centers.
The AI infrastructure boom has supercharged Jabil's growth. So, there is a solid chance of Jabil stock taking off after it releases its fiscal 2026 Q4 results on Sept. 30. Let's look at the reasons why Jabil could make a parabolic move after its quarterly report.

Image source: Getty Images.
Jabil's growth could exceed expectations once again
Jabil's earnings per share (EPS) have exceeded Wall Street's expectations in each of the last four quarters. This trend is likely to continue when Jabil releases its fiscal Q4 report, primarily driven by robust demand for its AI infrastructure offerings.
Jabil manufactures AI server racks, thermal management, and liquid-cooled systems. What's more, it builds networking products, including silicon photonics and optical components, apart from offering robotics and physical AI infrastructure manufacturing services. In simple words, Jabil is serving fast-growing AI-related markets, which could help it post better-than-expected results.
The company anticipates $9.6 billion in fiscal Q4 revenue at the midpoint, while adjusted earnings per share could land at $4.00. That points to a year-over-year jump of 11.5% in revenue and a 21.5% increase in earnings per share. However, analysts expect Jabil to post $4.07 in earnings per share on revenue of $9.7 billion.
The growing traction of Jabil's AI business could indeed help it beat estimates. After all, Jabil has been consistently raising its fiscal 2026 guidance throughout the year, primarily due to AI. The company expects $13.6 billion in AI revenue in fiscal 2026, up 51% from last year. What's worth noting is that Jabil originally anticipated a 25% increase in AI-related revenue in fiscal 2026.
However, strong AI infrastructure demand has led to upward revisions to Jabil's guidance. A similar picture could emerge when it releases its quarterly report this month, especially considering that investments in AI data center infrastructure aren't slowing down.
Consulting giant PwC expects data center spending could jump to a whopping $31.6 trillion by 2050. The firm adds that annual data center capex is on track to jump from $800 billion in 2026 to $1.8 trillion in 2050, suggesting that the primary tailwind driving Jabil's robust growth is here to stay.
This is why there is a strong likelihood that Jabil will deliver better-than-expected guidance, which should give the stock a big boost following its results, especially given its attractive valuation.
The stock's valuation sets it up for a parabolic move
Jabil trades at an attractive 19 times forward earnings, a discount to the tech-focused Nasdaq-100 index's forward earnings multiple of 25. Its earnings are anticipated to increase by 31% in fiscal 2026 to $12.77 per share.
Even better, analysts expect Jabil to sustain healthy earnings growth for the next couple of years.
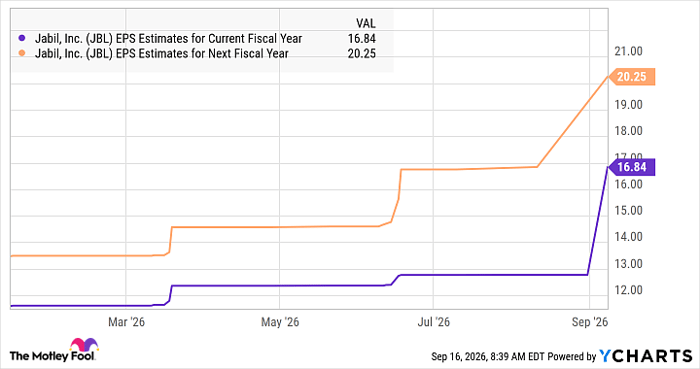
JBL EPS Estimates for Current Fiscal Year data by YCharts
Assuming Jabil's bottom line reaches $20.25 per share in earnings after a couple of years, and it trades at 25 times earnings at that time, in line with the Nasdaq-100 index's forward earnings multiple, its stock price could reach $511. That suggests a potential 73% jump, though don't be surprised to see a bigger jump in this AI stock given its ability to deliver stronger-than-expected growth, which should ideally be rewarded with a higher valuation.
So, investors looking to buy a top tech stock trading at an attractive valuation to capitalize on the AI infrastructure boom can consider buying Jabil before it makes a big move.
Should you buy stock in Jabil right now?
Before you buy stock in Jabil, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Jabil wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $412,074!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,314,319!*
Now, it’s worth noting Stock Advisor’s total average return is 935% — a market-crushing outperformance compared to 210% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of September 17, 2026.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Micron Technology. The Motley Fool has a disclosure policy.
Recommended Articles


