


People Keep Paying for Trash Pickup. Here's Why I'd Buy the Company Collecting the Checks.
Key Points
Garbage processing is an often-overlooked business, but WM has delivered steady growth and profits.
The company's ample free cash flow supports shareholder returns via stock buybacks and a regular dividend.
The company's debt load does pose a risk and bears watching -- especially as interest rates remain elevated.
- Motley Fool Issues Rare "Total Conviction" Buy Alert ›
Nobody overlooks when the garbage truck fails to arrive. Trash collection is one of those services that fades into the background of life -- until it doesn't happen.
For investors, this business is worth a closer look. Waste Management (NYSE: WM) gets paid to handle something everyone needs but no one really wants to think about. Behind the trucks is an impressive infrastructure network – and a business that returns value to shareholders.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
A service everyone needs
We've all been there. You miss trash day, and before you know it, you're seemingly knee-deep in all the stuff you really don't want to be knee-deep in. For Waste Management -- also known as WM -- this scenario creates a steady stream of demand for the collection, processing, and disposal of waste products. Indeed, WM already has about 20 million residential, commercial, industrial, and municipal customers across the U.S., Canada, and Puerto Rico.
While most consumers' experience with their trash ends at the curb, curbside pickup is only the starting point for WM. The company runs thousands of routes daily, picking up waste, transporting it to processing facilities, and disposing of it. In truth, this makes WM as much of a logistics business as FedEx or United Parcel Service. Processing facilities and pickup routes can serve as assets. One of WM's main competitive advantages is its existing infrastructure network and route coverage. Adding a new customer along an existing route can drive efficiency and profitability.
Where the shareholder returns come from
Ultimately, a stock's value comes from its potential to deliver future cash flows. For example, a company with robust free cash flow can drive shareholder value in a few ways: Paying dividends or buying back its own stock are the two most obvious ways to do so directly.
Free cash flow is the money left over after a company spends on equipment and facilities. WM has generated about $3 billion in free cash flow during the first nine months of 2026. That's up 42% from a year ago. With that free cash flow, the company can maintain its fleet, improve its facilities, pay down debt, or return value to shareholders through dividends or stock buybacks. Speaking of which, WM already has a $3 billion share repurchase agreement. As for dividends, the stock already boasts a yield of 1.6%.
What to expect from owning WM
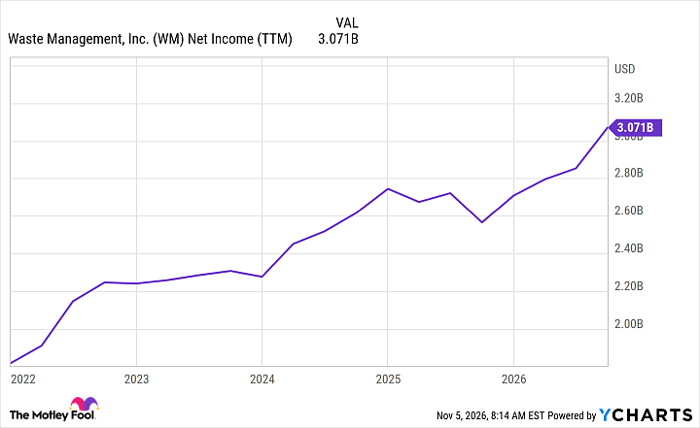
Sure, waste processing is reliable, but does it produce growth? In short, the answer is yes, at least for WM. Over the last five years, the company has grown revenue by an average of 8.7% year over year. Since 2021, net income has surged 69% from $1.8 billion to nearly $3.1 billion, an annualized rate of about 11%. Granted, it's not "knock your socks off" growth, but it's steady and reliable, like the business itself.
WM Net Income (TTM) data by YCharts.
However, investors shouldn't assume that WM stock comes with zero risk. Like any stock, price matters. WM stock currently sports a price-to-earnings (P/E) multiple of 31x. That's slightly above the S&P 500 average of 25.9. However, it's slightly below WM's 5-year average P/E of 32.6. That doesn't mean WM is cheap, but it does offer some comfort that the stock isn't severely overpriced relative to its own history.
Another key risk is operational. WM relies on several factors that could put pressure on it: labor, equipment, energy costs, and debt. Rising wages and fuel prices could eat into the company's margins. Equipment must be repaired and upgraded, which can drag on free cash flow. Finally, WM has over $23 billion in net debt. With interest rates already at their highest levels in years, WM's debt load is becoming more expensive.
Is WM a buy?
For many investors, WM is a stable stock that is worth considering. Its consistent growth in both revenue and profits shows that even though waste processing isn't sexy, it can be lucrative. Indeed, the same routine that makes trash pickup easy to overlook can also make the business a decent investment opportunity.
Should you buy stock in WM right now?
Before you buy stock in WM, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and WM wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004... if you invested $1,000 at the time of our recommendation, you’d have $341,966!* Or when Nvidia made this list on April 15, 2005... if you invested $1,000 at the time of our recommendation, you’d have $1,146,819!*
Now, it’s worth noting Stock Advisor’s total average return is 852% — a market-crushing outperformance compared to 203% for the S&P 500. Don't miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
See the 10 stocks »
*Stock Advisor returns as of November 9, 2026.
Jake Lerch has positions in United Parcel Service. The Motley Fool has positions in and recommends United Parcel Service. The Motley Fool recommends FedEx and WM. The Motley Fool has a disclosure policy.
Recommended Articles


